Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASA
USD 10.97 BN
MARKET SIZE, 2033

CAGR 11.1%
(2026-2033)

350
REPORT PAGES

150
MARKET TABLES
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
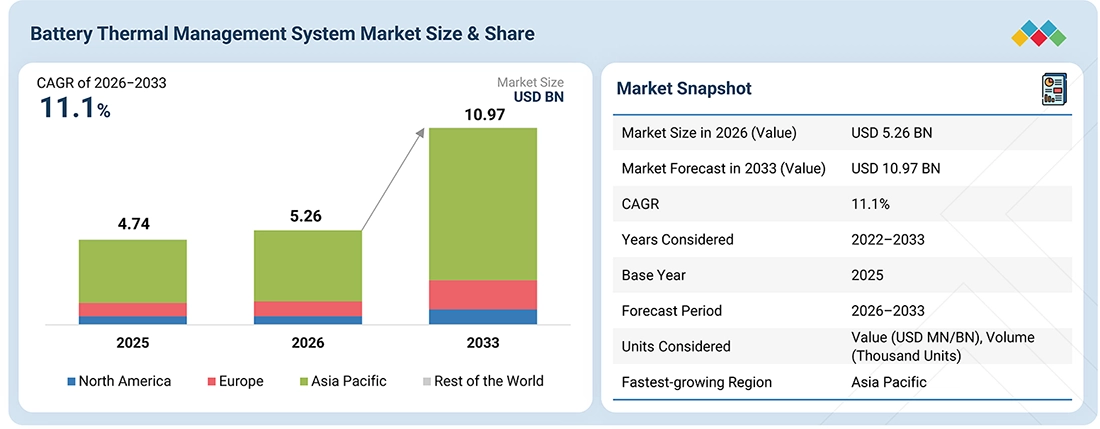
The battery thermal management system (BTMS) market size is projected to grow from USD 5.26 billion in 2026 to USD 10.97 billion by 2033 at a CAGR of 11.1%. The market is shifting toward better cell-level temperature control, higher cooling capacity, and improved temperature uniformity as EV batteries adopt higher energy density and faster charging. The focus is also moving from standalone battery cooling to integrated thermal management systems that manage the battery, e-motor, inverter, onboard charger, DC-DC converter, HVAC, and heat pump together. OEMs like Tesla, BMW, and Tier 1 suppliers such as Robert Bosch, Valeo, Gentherm, and Denso are developing liquid cooling systems using cold plates, refrigerant-based cooling, thermal interface materials, and temperature sensors to control hotspots and maintain uniform battery temperatures during fast charging and high-load operation. Immersion cooling is also being developed for high-power battery applications, while predictive thermal control and battery preconditioning are being used to manage battery temperature before and during fast charging.
By Region
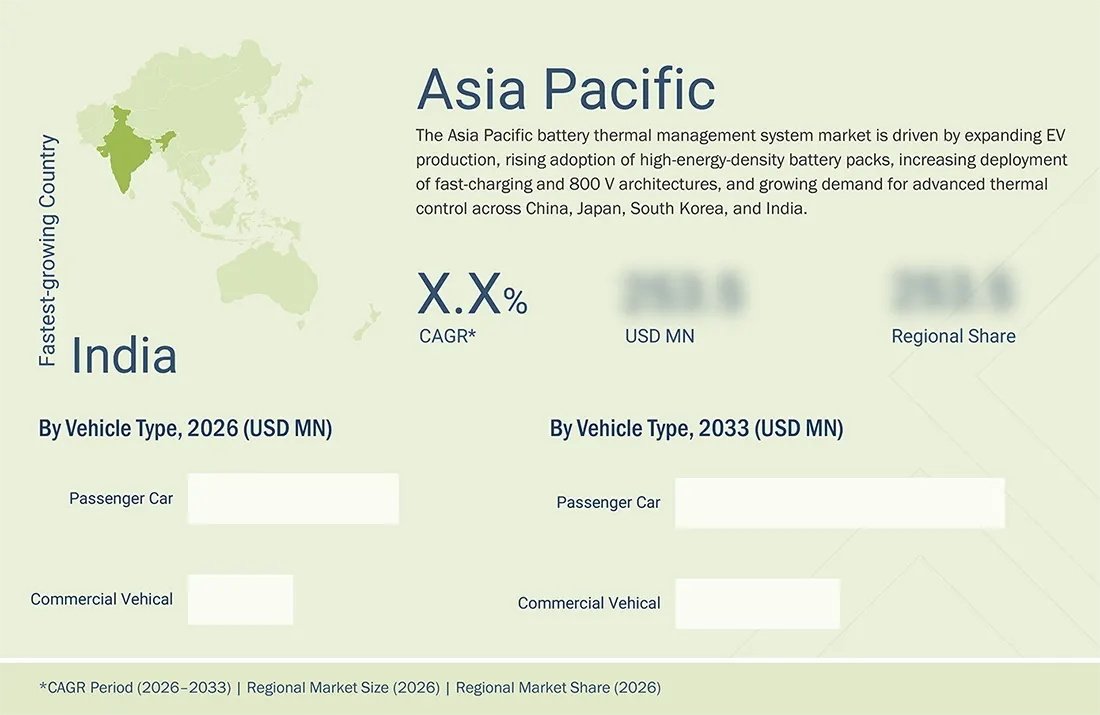
Asia Pacific is expected to be the largest market during the forecast period.
By Battery Type
Lithium-ion is estimated to dominate the battery thermal management system market, with a CAGR of 11.1% from 2026 to 2033.
BY Vehicle Type
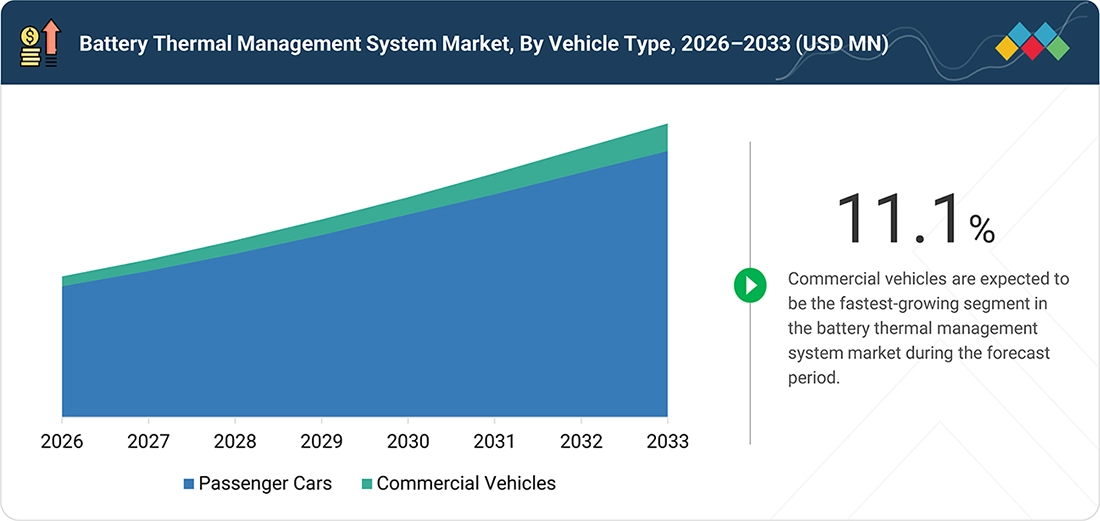
Passenger cars are projected to have the highest share, at 93.0%, in 2026.
BY Technology
Hybrid is estimated to be the fastest-growing segment of the battery thermal management system market, with a CAGR of 15.1% from 2026 to 2033.
BY Battery Capacity
50-100 kWh is expected to register the largest share of 71.1% in 2033.
By Propulsion
Battery electric vehicles are expected to be the fastest, with a CAGR of 12.7% from 2026 to 2033.
By Offering
BTMS with battery is expected to be the fastest-growing segment of the battery thermal management system market with a CAGR of 13.7% from 2026 to 2033.
By Component
Cooling plates are estimated to have a significant share in the battery thermal management system market in 2026.
COMPETITIVE LANDSCAPE (KEY PLAYERS)
Leading BTMS players, including Robert Bosch GmbH (Germany), Gentherm Incorporated (US), Valeo SE (France), AUMOVIO (Germany), and DENSO Corporation (Japan), are developing battery thermal management solutions across EV and hybrid platforms, with a focus on liquid cooling, thermal control components, integrated vehicle thermal systems, and temperature management for high-power and fast-charging applications.
COMPETITIVE LANDSCAPE (STARTUPS/SMES)
The market also includes companies such as LEM International SA (Switzerland), Orion BMS (US), Renesas Electronics Corporation (Japan), 3M (US), and Infineon Technologies AG (Germany), which provide battery sensing, battery management, semiconductor, thermal interface material, and electronic control technologies supporting BTMS and broader EV battery thermal management architectures.
The BTMS market is being shaped by the need to optimize thermal performance across the battery pack rather than focusing only on heat removal. Battery suppliers and thermal technology providers such as CATL and LG Energy Solution integrate thermal management into battery pack architectures, while MAHLE, Modine, and Webasto provide dedicated BTMS and integrated vehicle thermal management systems covering cooling, heating, chillers, pumps, and controls. At the pack level, thermal propagation control is also driving changes in module barriers, enclosure design, venting paths, and cell isolation to contain heat generated during abnormal operating conditions. In parallel, suppliers are integrating temperature and pressure sensing closer to the cell and coolant circuits to enable faster detection of thermal anomalies and more precise control of individual cooling zones.
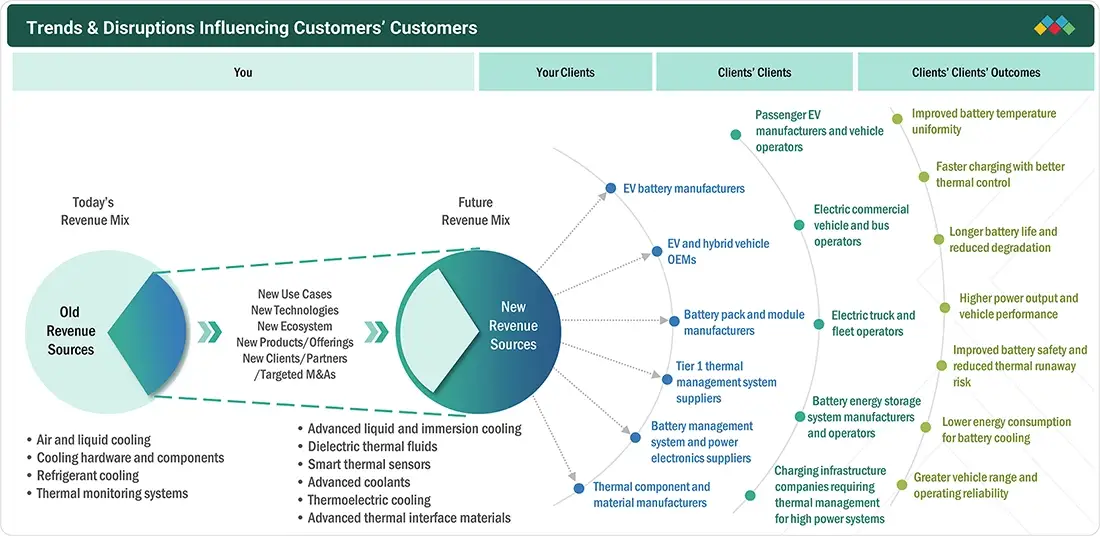
The battery thermal management system market is shifting from revenue concentrated in passenger EV battery cooling toward broader applications across electric commercial vehicles, electric trucks, fleet vehicles, battery energy storage systems, and high-power charging infrastructure. Current revenue is primarily tied to thermal components installed within vehicle battery packs, while future revenue opportunities are expected to expand through thermal management systems designed for continuous high-power operation, rapid charging, and larger battery systems. This shift creates additional revenue opportunities for suppliers through battery cooling, thermal sensing, refrigerant circuits, battery heaters, and thermal control systems across multiple high-power applications. As commercial EVs, fleet vehicles, and charging systems require higher thermal loads to be managed for longer operating periods, suppliers can capture additional revenue through larger-scale and more integrated thermal management solutions.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Drivers
Impact
Level


RESTRAINTS
Impact
Level


OPPORTUNITIES
Impact
Level


CHALLENGES
Impact
Level


Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Fast charging is shifting BTMS design from basic heat removal toward active control of battery temperature throughout the charging cycle. Battery and thermal system suppliers are developing higher-capacity cooling circuits, faster coolant flow control, and charging-related thermal control strategies to keep cells within their preferred temperature range as charging power increases. This is also increasing the importance of battery preconditioning, where thermal systems bring the pack to a suitable temperature before high-power charging begins. As charging power rises, BTMS performance directly affects charging time, cell aging, and usable charging power, making thermal capability an important part of EV charging system design.
BTMS design requires a balance between cooling capacity, system size, weight, and auxiliary energy consumption. Larger cold plates, pumps, heat exchangers, and coolant circuits can improve heat transfer but consume additional pack and vehicle space and increase system weight. Higher coolant flow can improve heat removal, but also increases pump power and reduces overall vehicle efficiency. This creates engineering constraints for compact battery packs, where thermal hardware must deliver sufficient heat transfer without reducing available space for cells or increasing the energy required to operate the thermal system.
Integration of battery cooling with the vehicle thermal architecture is expanding the scope of BTMS suppliers beyond battery-specific hardware. Thermal systems can share heat exchangers, pumps, valves, refrigerant circuits, and control logic across the battery, e-motor, inverter, onboard charger, and cabin systems. This enables waste heat from power electronics and the motor to be redirected for battery or cabin heating, while battery cooling can be coordinated with vehicle level heat rejection. As a result, suppliers capable of controlling multiple thermal circuits can capture value across several vehicle thermal functions rather than supplying only the battery cooling system.
Advanced BTMS requires close coordination between battery management systems, vehicle control units, HVAC controls, charging systems, and thermal hardware. Changes in battery temperature, charging power, vehicle load, and ambient conditions can require simultaneous adjustments to pumps, valves, compressors, and coolant circuits. Poor coordination can increase unnecessary thermal system operation and auxiliary power consumption even when battery cooling demand is low. This makes software control logic, communication between thermal and vehicle controllers, and real-time thermal demand estimation important for integrating advanced BTMS without reducing overall vehicle efficiency.
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
|
|
Provides battery and powertrain thermal management through electric coolant pumps, refrigerant compressors, coolant valves, heat pumps, pre integrated thermal modules, and predictive thermal control software for EVs and hybrids | Helps OEMs maintain battery temperature within the required operating range, improve fast charging performance, reduce thermal stress on batteries and e powertrain components, and simplify thermal system integration |
|
|
Provides battery heating, battery air cooling, thermoelectric heating and cooling, direct evaporative liquid cooling, and cell connecting technology for hybrid and electric vehicle battery systems | Enables precise battery temperature control across hot and cold conditions, supports battery performance and lifetime, improves charging capability, and provides compact thermal solutions for low voltage and high voltage battery applications |
|
|
Supplies refrigerant, liquid, air, and immersive battery cooling systems, battery coolers, battery chillers, and associated thermal control solutions for hybrid, PHEV, and BEV applications | Helps OEMs control cell temperature and temperature uniformity, support high power and fast charging, protect batteries from thermal stress, and integrate battery cooling with vehicle air conditioning and heat pump systems |
|
|
Provides battery management and sensing solutions with integrated thermal management functions, including high voltage current sensing, cell temperature monitoring, thermal control software, coolant temperature and flow monitoring, and control of fans, pumps, and valves | Gives OEMs real time battery temperature and electrical data for thermal control, diagnostics, safety management, and battery state estimation, while supporting integration of battery thermal management with the vehicle control architecture |
|
|
Provides EV thermal management systems covering battery and inverter cooling, heat pumps, electric compressors, electric water pumps, radiators, chillers, and multi flow coolant control valves | Helps OEMs maintain optimum battery and inverter temperatures, improve energy efficiency and driving range, support shorter charging times, and coordinate battery, power electronics, and cabin thermal management |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
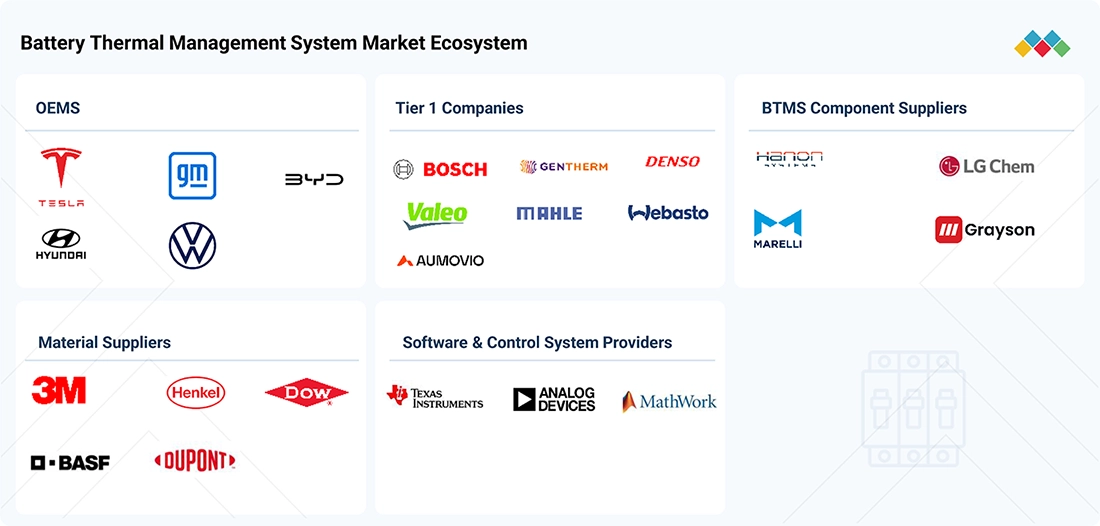
The battery thermal management system market ecosystem is shifting from individual cooling components toward integrated battery and vehicle thermal management solutions. Vehicle OEMs integrate battery thermal systems with vehicle level thermal architectures, while BTMS component suppliers provide cooling modules, pumps, valves, heat exchangers, and related hardware. Material suppliers support the ecosystem through thermal interface materials, adhesives, encapsulants, and other materials used for heat transfer and thermal protection. Tier 1 suppliers develop complete thermal management systems by integrating multiple hardware components into vehicle platforms. Software and control system providers support sensing, modeling, thermal control, and system level energy management. Coordination across these participants is enabling suppliers to move from individual components toward integrated thermal architectures, while increasing the role of control software and advanced materials in overall BTMS performance.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Lithium-ion batteries are expected to account for a significant market share as their high energy density and high power requirements increase the need for active cooling to control cell temperature and maintain battery performance.
Passenger cars are expected to account for the largest market share as EV passenger platforms increasingly use liquid-cooled battery packs to manage thermal loads within compact battery enclosures.
Hybrid BTMS technology is expected to witness the fastest growth as hybrid vehicles require coordinated thermal control for the battery, engine, motor, inverter, and other powertrain components under frequent changes in operating conditions.
50 -100 kWh battery packs are expected to account for the largest market share as this capacity range requires higher thermal control capability to manage heat generated during charging, acceleration, and sustained vehicle operation.
BTMS with battery is expected to witness the fastest growth as battery pack suppliers increasingly integrate thermal hardware directly with battery assemblies, reducing thermal interface complexity and enabling closer control of cell temperature.
Cooling plates are expected to account for a significant market share as direct contact with battery cells or modules enables efficient heat transfer and supports uniform temperature control across the battery pack.
Battery electric vehicles are expected to witness the fastest growth in the BTMS market, driven by higher battery power requirements, fast charging, and the need for continuous temperature control across high-capacity battery packs.
In Asia Pacific, the battery thermal management system market is being shaped by the shift toward battery pack-level thermal integration, particularly in China, Japan, and South Korea. Chinese battery and EV manufacturers like CATL and BYD are adopting liquid cooling with integrated cold plates, coolant channels, and thermal control hardware across high-energy-density battery packs, while Japanese suppliers such as Panasonic Automotive Systems are developing battery heating, battery cooling fans, and temperature sensing technologies, supporting tighter temperature control within vehicle battery systems. South Korean companies such as LG Energy Solution and Samsung SDI are focusing on pack-integrated cooling and thermal propagation control. This is creating a regional shift toward BTMS architectures designed together with battery cells and pack structures, with greater emphasis on cell-level temperature control, thermal propagation management, fast charging capability, and efficient use of limited pack space rather than treating battery cooling as a separate vehicle subsystem.
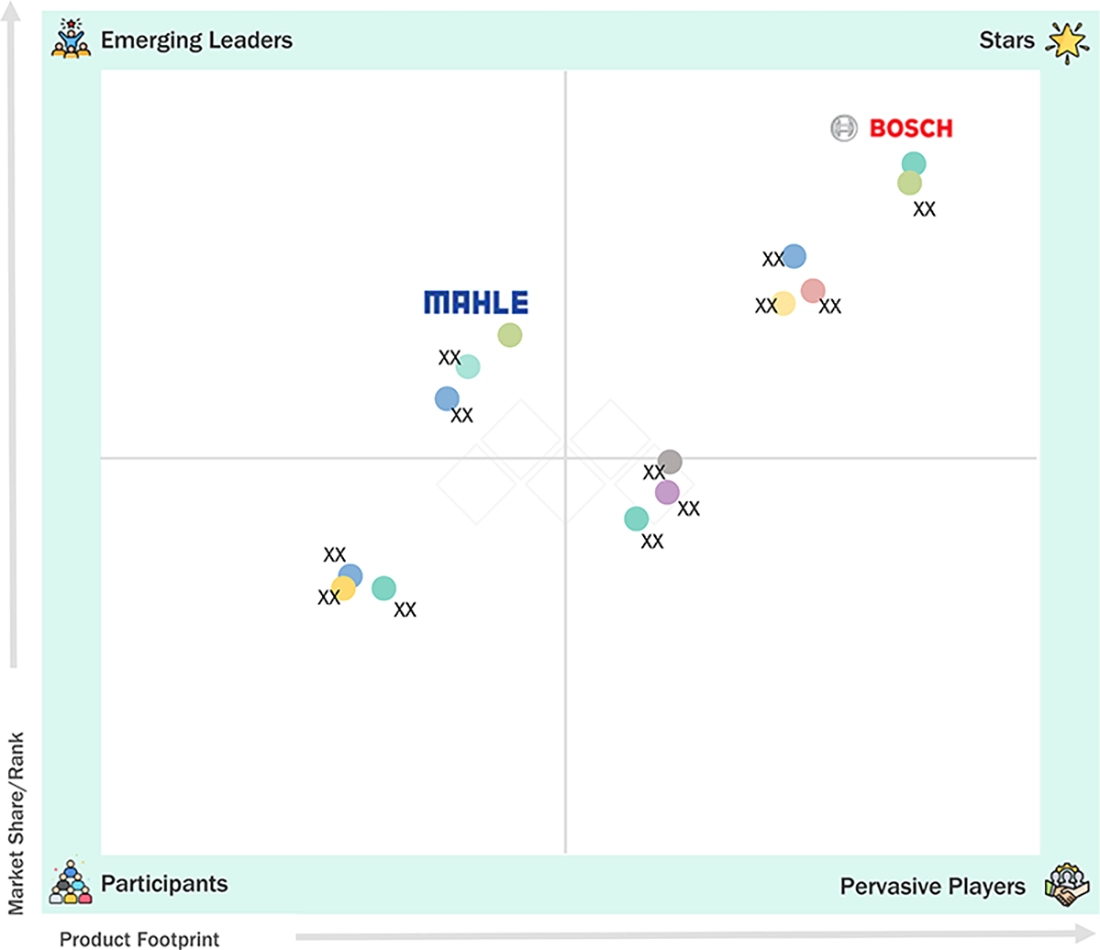
In the battery thermal management system market matrix, Robert Bosch GmbH (Star) leads through its broad thermal management portfolio, including battery cooling systems, thermal management modules, sensors, and control technologies, supported by its integration capabilities across vehicle thermal and powertrain systems. MAHLE GmbH (Emerging Leader) is strengthening its position through battery cooling and thermal management solutions for electrified vehicles, with a focus on compact cooling architectures, heat exchangers, and integrated thermal systems designed to manage battery and powertrain heat loads.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 5.26 BN |
| Market Forecast in 2033 (Value) | USD 10.97 BN |
| Growth Rate | CAGR of 11.1% from 2026 to 2033 |
| Years Considered | 2022–2033 |
| Base Year | 2025 |
| Forecast Period | 2026–2033 |
| Units Considered | Value (USD MN/BN), Volumne (Thousand Units) |
| Report Coverage | Revenue forecast, company share, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | Asia Pacific, Europe, North America, Rest of the World |
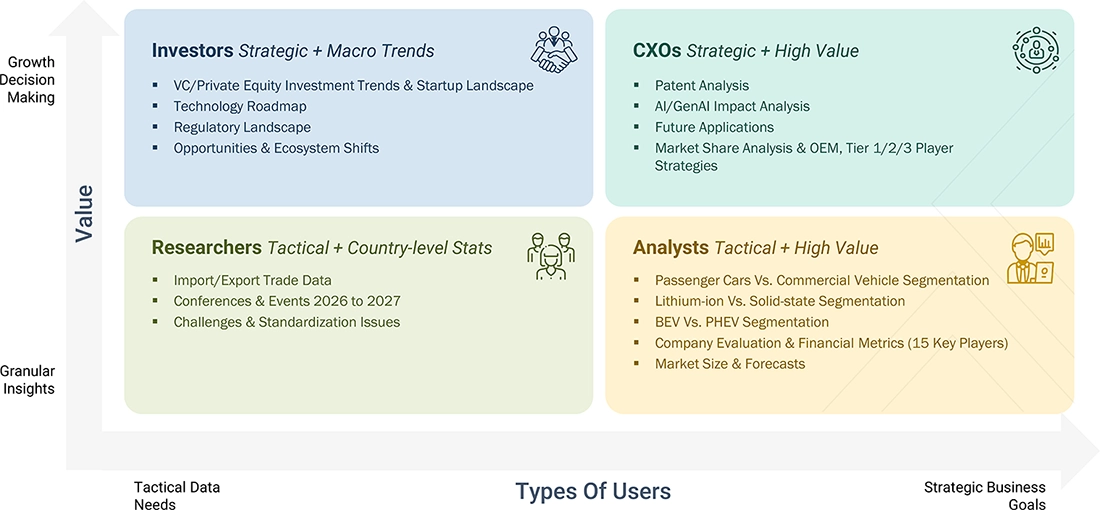
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Global EV OEM (US) | Competitive intelligence on leading BTMS suppliers, assessment of liquid cooling architectures, cold plate designs, coolant circuits, thermal control strategies, and integration with battery packs and vehicle thermal systems |
|
| EV OEM (Asia) | Model level analysis of battery pack thermal architectures, cooling plate configurations, cell temperature control, thermal propagation protection, and fast charging thermal strategies |
|
| Commercial EV OEM (Europe) | Benchmarking of BTMS architectures for electric trucks and buses, including high-capacity battery cooling, coolant flow management, thermal propagation control, and high-load duty cycle requirements |
|
| Tier 1 Supplier (Europe) | Technology intelligence on cold plates, pumps, valves, heat exchangers, sensors, thermal interface materials, refrigerant cooling, and integrated thermal management modules, with OEM and supplier mapping |
|
| Battery Manufacturer (Asia) | Assessment of BTMS integration with battery cells and packs, including thermal interface materials, cooling channel geometry, cell spacing, temperature sensing, and thermal propagation barriers |
|
| BTMS Component Supplier (Asia) | Benchmarking of cooling plates, thermal interface materials, pumps, valves, sensors, and control components across EV battery platforms, including technical specifications and sourcing patterns |
|
| Software and Controls Provider (US) | Assessment of battery thermal control strategies, thermal models, sensor inputs, predictive temperature estimation, charging preconditioning, and communication between BMS and vehicle thermal controllers |
|
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
35
2
EXECUTIVE SUMMARY
45
3
PREMIUM INSIGHTS
51
4
MARKET OVERVIEW
Higher battery power density and fast charging redefine thermal management and integration strategies in EV markets.56
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
HIGHER BATTERY POWER DENSITY DRIVING TIGHTER CELL-LEVEL TEMPERATURE CONTROL
4.2.1.2
FAST CHARGING PERFORMANCE MAKING BTMS CORE CHARGING-ENABLER
4.2.2
RESTRAINTS
4.2.2.1
CELL-TO-PACK THERMAL NON-UNIFORMITY LIMITING HIGH-POWER AND FAST-CHARGING CAPABILITY
4.2.2.2
BTMS PERFORMANCE, PACKAGING AND ENERGY TRADE-OFF LIMITING SYSTEM OPTIMIZATION
4.2.3
OPPORTUNITIES
INTEGRATED THERMAL MANAGEMENT PLATFORMS EXPANDING BTMS
4.2.3.2
IMMERSION COOLING ADOPTION FOR COMMERCIAL EV BATTERIES
PREDICTIVE THERMAL INTELLIGENCE ENABLING FAST CHARGING AND
4.2.4
CHALLENGES
MAINTAINING CELL-LEVEL THERMAL UNIFORMITY UNDER HIGH-POWER
4.3
UNMET NEEDS AND WHITE SPACES
THERMAL PERFORMANCE GAP DURING ULTRA FAST CHARGING
THERMAL MANAGEMENT OF HIGH-ENERGY-DENSITY AND
LIMITED THERMAL SOLUTIONS FOR HIGH-UTILIZATION
4.4
STRATEGIC OUTLOOK AND GROWTH OPPORTUNITIES
4.4.1
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.4.1.1
INTERCONNECTED MARKETS
4.4.1.2
CROSS-SECTOR OPPORTUNITIES
4.4.2
STRATEGIC MOVES BY OEMS AND TIER 1 & TIER 2/3 PLAYERS
5
INDUSTRY TRENDS
Emerging battery thermal management tech reshapes EV industry with innovative cooling solutions and pricing dynamics.69
5.1
MACROECONOMIC INDICATORS
5.1.1
INTRODUCTION
5.1.2
GDP TRENDS AND FORECAST
5.1.3
TRENDS IN GLOBAL THERMAL BATTERY MANAGEMENT INDUSTRY
5.1.4
TRENDS IN GLOBAL ELECTRIC VEHICLE BATTERY INDUSTRY
5.2
PRICING ANALYSIS
5.2.1
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS OFFERED BY KEY PLAYERS, BY PROPULSION
5.2.2
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY PROPULSION
5.2.3
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY VEHICLE TYPE AND REGION
5.3
ECOSYSTEM ANALYSIS
5.4
OEM REQUIREMENTS FOR BTMS
5.4.1
THERMAL UNIFORMITY & HEAT-FLUX MANAGEMENT
5.4.2
FAST CHARGING THERMAL MANAGEMENT
5.4.3
INTEGRATED VEHICLE THERMAL MANAGEMENT
5.5
VALUE CHAIN ANALYSIS
5.6
CASE STUDY ANALYSIS
5.6.1
ADVANCED BATTERY THERMAL MANAGEMENT FROM AIR COOLING TO IMMERSION COOLING
5.6.2
THERMAL PROPAGATION BARRIER FOR EV BATTERY PACKS
5.6.3
INTEGRATED DUAL-SIDED LIQUID COOLING SYSTEM FOR ELECTRIC BUS BATTERIES
5.6.4
ADVANCED THERMAL CELL BARRIER FOR EV BATTERY PACKS
5.6.5
ENHANCEMENT OF EV PERFORMANCE WITH IMMERSION COOLING BATTERY TECHNOLOGY
5.7
INVESTMENT AND FUNDING SCENARIO
5.8
TRADE DATA (HS CODE 903289)
5.8.1
IMPORT TRADE DATA (HS CODE 903289)
5.8.2
EXPORT TRADE DATA (HS CODE 903289)
5.9
KEY CONFERENCES AND EVENTS, 2026–2027
5.10
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.11
OEM INTEGRATION OF BATTERY, POWERTRAIN, AND CABIN THERMAL SYSTEMS ANALYSIS
5.11.1
OEM X EV BATTERY AND POWERTRAIN THERMAL INTEGRATION
5.11.2
OEM, EV BATTERY, AND CABIN THERMAL INTEGRATION
5.11.3
OEM X BTMS PLATFORM STRATEGY
5.11.4
OEM X TIER 1 TECHNOLOGY & SOURCING STRATEGY
5.12
BILL OF MATERIALS OF BATTERY THERMAL MANAGEMENT SYSTEMS
5.12.1
THERMAL INTERFACE MATERIALS & INSULATION
5.12.2
REFRIGERANT CIRCUIT HARDWARE
5.12.3
REFRIGERANT CIRCUIT INTERFACE
5.12.4
THERMAL SENSORS
5.12.5
COOLANT CIRCUITS
5.12.6
BTMS CONTROLLERS & WIRING
5.12.7
VALVES/EXPANSION VALVES
5.12.8
BATTERY HEATERS
5.12.9
PUMPS/FANS
5.12.10
BATTERY CHILLERS
5.12.11
COOLING PLATES
5.13
BTMS EVOLUTION BY BATTERY ARCHITECTURE
5.13.1
MODULE BATTERY
5.13.2
CELL-TO-PACK (CTP)
5.13.3
STRUCTURAL BATTERY
5.13.4
CELL-TO-BODY (CTB)
5.13.5
CELL-TO-CHASSIS
5.13.6
INTEGRATED BATTERY CHASSIS
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven thermal innovations redefine future cooling systems and vehicle thermal management strategies.101
6.1
PATENT ANALYSIS
6.2
TECHNOLOGY ANALYSIS
6.2.1
KEY TECHNOLOGIES
6.2.1.1
IMMERSION COOLING
6.2.1.2
ADVANCED LIQUID COOLING AND COOLING PLATES
6.2.1.3
REFRIGERANT-BASED COOLING SYSTEMS
6.2.2
COMPLEMENTARY TECHNOLOGIES
6.2.2.1
ADVANCEMENTS IN THERMAL SENSORS
6.2.2.2
PHASE CHANGE MATERIALS
6.2.2.3
AI-BASED PREDICTIVE THERMAL CONTROL
6.2.3
ADJACENT TECHNOLOGIES
6.2.3.1
FAST CHARGING THERMAL CONDITIONING
6.2.3.2
HIGH VOLTAGE E COMPRESSORS AND THERMAL ACTUATORS
6.2.3.3
INTEGRATED HEAT PUMP AND VEHICLE THERMAL MANAGEMENT
6.3
PRODUCT/TECHNOLOGY ROADMAP
6.3.1
BTMS ARCHITECTURE EVOLUTION
6.3.1.1
STANDALONE BATTERY COOLING
6.3.1.2
INTEGRATED BATTERY/POWERTRAIN
6.3.1.3
INTEGRATED VEHICLE THERMAL MANAGEMENT
6.3.1.4
PREDICTIVE AND ADAPTIVE VEHICLE THERMAL ARCHITECTURE
6.3.2
THERMAL MANAGEMENT TECHNOLOGY ROADMAP
6.3.2.1
AIR COOLING
6.3.2.2
INDIRECT LIQUID
6.3.2.3
ADVANCED COLD PLATES
6.3.2.4
PCM/HYBRID COOLING
6.3.2.5
IMMERSION/TWO-PHASE COOLING
6.4
EU–INDIA FTA IMPACT ANALYSIS
6.4.1
EU TARIFFS
6.4.2
IMPORT TO INDIA
6.4.3
EXPORT FROM INDIA
6.5
IMPACT OF 2026 ISRAEL-IRAN CONFLICT ON BATTERY THERMAL MANAGEMENT SYSTEM MARKET
6.5.1
RAW MATERIAL AND COMPONENT PRICE VOLATILITY
6.5.2
SUPPLY CHAIN AND LOGISTICS DISRUPTIONS
6.5.3
PRODUCT DEVELOPMENT AND VEHICLE PROGRAM DELAYS
6.5.4
REGIONAL EFFECTS
6.6
IMPACT OF AI ON BATTERY THERMAL MANAGEMENT SYSTEM MARKET
6.6.1
TOP USE CASES AND MARKET POTENTIAL
6.6.2
BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN BATTERY THERMAL MANAGEMENT SYSTEM MARKET
6.6.3
CASE STUDIES RELATED TO IMPLEMENTATION OF AI IN BATTERY THERMAL MANAGEMENT SYSTEM MARKET
6.6.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.6.5
CLIENTS’ READINESS TO ADOPT AI INTEGRATION IN BATTERY THERMAL MANAGEMENT SYSTEM MARKET
7
REGULATORY AND SUSTAINABILITY LANDSCAPE
Discover global battery regulations driving sustainability and circular economy advancements.124
7.1
REGULATORY ANALYSIS
7.1.1
KEY REGULATIONS
7.1.1.1
EUROPEAN UNION (EU)
7.1.1.2
INDIA
7.1.1.3
CHINA
7.1.1.4
CANADA
7.1.1.5
US
7.1.2
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.2
SUSTAINABILITY INITIATIVES
7.2.1
CHINA: BATTERY CIRCULARITY AND LIFECYCLE MANAGEMENT INITIATIVES
7.2.2
EUROPE: BATTERY CARBON FOOTPRINT AND CIRCULAR ECONOMY INITIATIVES
7.2.3
US: DOMESTIC BATTERY CIRCULARITY AND RESOURCE SECURITY INITIATIVES
7.2.4
JAPAN: ADVANCED BATTERY TECHNOLOGY AND ENERGY EFFICIENCY INITIATIVES
7.2.5
SOUTH KOREA: USED BATTERY CIRCULAR ECONOMY INITIATIVES
7.2.6
UAE: ELECTRIC MOBILITY AND LOW EMISSION TRANSPORT INITIATIVES
7.2.7
INDIA: DOMESTIC BATTERY MANUFACTURING AND BATTERY CIRCULARITY INITIATIVES
7.2.8
GERMANY: CIRCULAR ECONOMY AND RESOURCE EFFICIENCY INITIATIVES
7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Uncover strategic buyer insights to maximize market profitability in battery thermal management systems.134
8.1
DECISION-MAKING PROCESS
8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.2.2
KEY BUYING CRITERIA
8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES
8.3.1
MARKET PROFITABILITY
8.3.2
REVENUE POTENTIAL
8.3.3
COST DYNAMICS
8.4
MARGIN OPPORTUNITIES, BY APPLICATION
9
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 12 Data Tables139
9.1
INTRODUCTION
9.2
ACTIVE SYSTEMS
9.2.1
INCREASING DEMAND FOR HIGHER HEAT-REJECTION CAPACITY IN HIGH-DENSITY BATTERY PACKS TO DRIVE MARKET
9.2.2
AIR COOLING
9.2.3
LIQUID COOLING
9.2.4
THERMOELECTRIC COOLING
9.3
HYBRID SYSTEMS
9.3.1
COMBINING ACTIVE COOLING WITH THERMAL BUFFERING TO SUPPORT FAST CHARGING TO DRIVE MARKET
9.3.2
HEAT PIPE + AIR/LIQUID
9.3.3
PCM + AIR/LIQUID
9.3.4
PCM + HEAT PIPE
9.3.5
LIQUID + AIR
9.4
PASSIVE SYSTEMS
9.4.1
PHASE CHANGE MATERIAL (PCM)
9.4.2
HEAT PIPES
9.5
KEY PRIMARY INSIGHTS
10
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 30 Data Tables150
10.1
INTRODUCTION
10.2
LITHIUM-ION
10.2.1
LITHIUM IRON PHOSPHATE (LFP)
10.2.1.1
COST-DRIVEN EV ADOPTION IN HIGH-VOLUME PLATFORMS TO DRIVE GROWTH
10.2.2
LITHIUM NICKEL MANGANESE COBALT OXIDE (NMC)
10.2.2.1
HIGH ENERGY DENSITY REQUIREMENTS TO DRIVE GROWTH
10.2.3
LITHIUM IRON MANGANESE PHOSPHATE (LFMP)
10.2.3.1
UPGRADED THERMAL MANAGEMENT AND HIGHER-ENERGY LFP ARCHITECTURES TO DRIVE GROWTH
10.2.4
LITHIUM NICKEL COBALT ALUMINUM OXIDE (NCA)
10.2.4.1
HIGH PRECISION COOLING DEMAND TO DRIVE GROWTH
10.3
SOLID-STATE
10.3.1
TRANSITION TOWARD HIGHER ENERGY DENSITY TO DRIVE MARKET
10.4
KEY PRIMARY INSIGHTS
11
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 12 Data Tables165
11.1
INTRODUCTION
11.2
PASSENGER VEHICLE
11.2.1
INCREASING FAST-CHARGING CAPABILITY AND HIGH-VOLTAGE EV ADOPTION TO DRIVE MARKET
11.3
COMMERCIAL VEHICLE
11.3.1
RISING ELECTRIFICATION OF HIGH-UTILIZATION FLEETS AND HEAVY-DUTY VEHICLES TO DRIVE GROWTH
11.4
KEY PRIMARY INSIGHTS
12
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY CAPACITY
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 25 Data Tables172
12.1
INTRODUCTION
12.2
<50 KWH
12.2.1
INCREASING DEMAND FOR COMPACT AND COST-OPTIMIZED THERMAL ARCHITECTURES TO DRIVE GROWTH
12.3
50-100 KWH
12.3.1
EXPANDING FAST-CHARGING REQUIREMENTS IN MAINSTREAM EV PLATFORMS TO DRIVE MARKET
12.4
100–200 KWH
12.4.1
GROWING TREND OF LARGER-CAPACITY BATTERIES TO DRIVE GROWTH
12.5
200–500 KWH
12.5.1
INCREASING DEMAND FOR FASTER ACCELERATION AND GREATER POWER OUTPUT TO DRIVE GROWTH
12.6
>500 KWH
12.6.1
EXPANSION OF LONG-RANGE AND HEAVY-DUTY PLATFORMS TO DRIVE MARKET
12.7
KEY PRIMARY INSIGHTS
13
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY OFFERING
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 12 Data Tables186
13.1
INTRODUCTION
13.2
BTMS WITH BATTERY
13.2.1
INCREASING INTEGRATION OF THERMAL ARCHITECTURE INTO BATTERY-PACK DESIGN TO DRIVE MARKET
13.3
BTMS WITHOUT BATTERY
13.3.1
GROWING OEM PREFERENCE FOR MODULAR THERMAL-SYSTEM INTEGRATION TO DRIVE MARKET
13.4
KEY PRIMARY INSIGHTS
14
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million and Units | 12 Data Tables193
14.1
INTRODUCTION
14.2
BATTERY ELECTRIC VEHICLE (BEV)
14.2.1
INCREASING ULTRA-FAST CHARGING AND BATTERY PERFORMANCE REQUIREMENTS TO DRIVE MARKET
14.3
PLUG-IN HYBRID ELECTRIC VEHICLE (PHEV)
14.3.1
RISING BATTERY CAPACITY AND DUAL-POWERTRAIN THERMAL INTEGRATION TO DRIVE MARKET
14.4
FUEL CELL ELECTRIC VEHICLE (FCEV)
14.5
KEY PRIMARY INSIGHTS
15
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COMPONENT
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 26 Data Tables201
15.1
INTRODUCTION
15.2
THERMAL SENSORS
15.2.1
INCREASING REQUIREMENT FOR CELL-LEVEL TEMPERATURE MONITORING TO DRIVE DEMAND
15.3
COOLING PLATES
15.3.1
RISING FAST-CHARGING AND BATTERY ENERGY DENSITY REQUIREMENTS TO DRIVE DEMAND
15.4
HEAT PIPES
15.4.1
EXPANDING USE OF PASSIVE HEAT TRANSFER FOR TEMPERATURE UNIFORMITY TO DRIVE DEMAND
15.5
PUMPS/FANS
15.5.1
INCREASING DEMAND FOR CONTROLLED COOLANT CIRCULATION TO DRIVE MARKET
15.6
BATTERY CHILLERS
15.6.1
INTEGRATION OF BATTERY COOLING WITH VEHICLE REFRIGERATION SYSTEMS TO DRIVE GROWTH
15.7
HEAT EXCHANGERS/RADIATORS
15.7.1
GROWING NEED FOR EFFICIENT HEAT REJECTION TO DRIVE MARKET
15.8
VALVES/EXPANSION VALVES
15.8.1
INCREASING PRECISION FLOW CONTROL TO DRIVE GROWTH
15.9
REFRIGERANT CIRCUIT HARDWARE
15.9.1
EXPANSION OF ACTIVE REFRIGERATION FOR HIGH-LOAD BATTERY CONDITIONING TO DRIVE MARKET
15.10
COOLANT CIRCUITS
15.10.1
INCREASING ADOPTION OF MULTI-LOOP LIQUID COOLING ARCHITECTURES TO DRIVE MARKET
15.11
BATTERY HEATERS
15.11.1
GROWING IMPORTANCE OF LOW-TEMPERATURE BATTERY CONDITIONING TO DRIVE DEMAND
15.12
BTMS CONTROLLERS & WIRING
15.12.1
TRANSITION TOWARD SOFTWARE-DEFINED THERMAL CONTROL TO DRIVE MARKET
15.13
THERMAL INTERFACE MATERIAL (TIM) & INSULATION
15.13.1
INCREASING THERMAL DENSITY REQUIREMENTS TO DRIVE MARKET
15.14
KEY PRIMARY INSIGHTS
16
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION
Comprehensive coverage of 7 Regions with country-level deep-dive of 15 Countries | 89 Data Tables.220
16.1
INTRODUCTION
16.2
ASIA PACIFIC
16.2.1
CHINA
16.2.1.1
INCREASING DEMAND FOR EVS AND ADVANCED THERMAL MANAGEMENT SOLUTIONS TO DRIVE MARKET
16.2.2
INDIA
16.2.2.1
EV INCENTIVES AND BATTERY MANUFACTURING PROGRAMS TO DRIVE MARKET
16.2.3
JAPAN
16.2.3.1
GROWING FOCUS ON DOMESTIC EV BATTERY MANUFACTURING TO DRIVE MARKET
16.2.4
SOUTH KOREA
16.2.4.1
GROWING EMPHASIS ON GREENHOUSE GAS EMISSION REDUCTION TO DRIVE MARKET
16.2.5
REST OF ASIA PACIFIC
16.3
EUROPE
16.3.1
FRANCE
16.3.1.1
EXPANSION OF ADVANCED BATTERY COOLING TECHNOLOGIES TO DRIVE MARKET
16.3.2
GERMANY
16.3.2.1
EXPANSION OF INTEGRATED EV THERMAL MANAGEMENT SOLUTIONS TO DRIVE MARKET
16.3.3
NORWAY
16.3.3.1
EXPANSION OF DOMESTIC BATTERY MANUFACTURING TO SUPPORT ADVANCED BTMS DEVELOPMENT
16.3.4
UK
16.3.4.1
INTEGRATION OF BATTERY THERMAL MANAGEMENT COMPONENTS TO DRIVE MARKET
16.3.5
SWEDEN
16.3.5.1
EXPANSION OF COMMERCIAL ELECTRIC VEHICLE FLEETS TO DRIVE MARKET
16.3.6
NETHERLANDS
16.3.6.1
NEED FOR ADVANCED THERMAL MANAGEMENT IN ELECTRIC TRUCKS TO DRIVE MARKET
16.3.7
REST OF EUROPE
16.4
NORTH AMERICA
16.4.1
US
16.4.1.1
EXPANSION OF BATTERY THERMAL MANAGEMENT CAPABILITIES TO DRIVE MARKET
16.4.2
CANADA
16.4.2.1
DEVELOPMENT OF ADVANCED BATTERY THERMAL MANAGEMENT TECHNOLOGIES TO DRIVE MARKET
16.5
REST OF THE WORLD (ROW)
16.5.1
UAE
16.5.1.1
ADVANCED BATTERY COOLING FOR HIGH AMBIENT CONDITIONS TO DRIVE MARKET
16.5.2
EGYPT
16.5.2.1
LOCALIZATION OF EV AND BATTERY MANUFACTURING TO DRIVE MARKET
16.5.3
SOUTH AFRICA
16.5.3.1
GROWING LOCAL BATTERY MANUFACTURING FOR ELECTRIC MOBILITY TO DRIVE MARKET
17
COMPETITIVE LANDSCAPE
Discover how key players outmaneuver rivals with strategic innovations and market dominance tactics.262
17.1
INTRODUCTION
17.2
KEY PLAYER STRATEGIES/RIGHT TO WIN, JANUARY 2024–SEPTEMBER 2026
17.3
REVENUE ANALYSIS, 2021–2025
17.4
MARKET SHARE ANALYSIS, 2025
17.5
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
17.5.1
STARS
17.5.2
EMERGING LEADERS
17.5.3
PERVASIVE PLAYERS
17.5.4
PARTICIPANTS
17.5.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025
17.5.5.1
COMPANY FOOTPRINT
17.5.5.2
REGION FOOTPRINT
17.5.5.3
TECHNOLOGY FOOTPRINT
17.5.5.4
BATTERY TYPE FOOTPRINT
17.5.5.5
VEHICLE TYPE FOOTPRINT
17.5.5.6
PROPULSION FOOTPRINT
17.6
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
17.6.1
PROGRESSIVE COMPANIES
17.6.2
RESPONSIVE COMPANIES
17.6.3
DYNAMIC COMPANIES
17.6.4
STARTING BLOCKS
17.6.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
17.7
COMPANY VALUATION AND FINANCIAL METRICS
17.8
BRAND/PRODUCT COMPARISON
17.9
COMPETITIVE SCENARIO
17.9.1
PRODUCT LAUNCHES AND DEVELOPMENTS
17.9.2
DEALS
17.9.3
EXPANSIONS
17.9.4
OTHER DEVELOPMENTS
18
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)285
18.1
KEY PLAYERS
18.1.1
ROBERT BOSCH GMBH
18.1.1.1
BUSINESS OVERVIEW
18.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
18.1.1.3
RECENT DEVELOPMENTS
18.1.1.3.1
DEALS
18.1.1.3.2
OTHER DEVELOPMENTS
18.1.1.4
MNM VIEW
18.1.1.4.1
RIGHT TO WIN
18.1.1.4.2
STRATEGIC CHOICES
18.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS
18.1.2
GENTHERM
18.1.3
VALEO
18.1.4
AUMOVIO
18.1.5
DENSO CORPORATION
18.1.6
MAHLE GMBH
18.1.7
BORGWARNER INC.
18.1.8
DANA LIMITED
18.1.9
GRAYSON THERMAL SYSTEMS
18.1.10
WEBASTO GROUP
18.1.11
LG CHEM
18.1.12
HANON SYSTEMS (HANKOOK & COMPANY GROUP)
18.2
OTHER PLAYERS
18.2.1
VOSS
18.2.2
MARELLI HOLDINGS CO., LTD.
18.2.3
LEM INTERNATIONAL SA
18.2.4
ORION BMS
18.2.5
RENESAS ELECTRONICS CORPORATION
18.2.6
3M
18.2.7
INFINEON TECHNOLOGIES AG
18.2.8
PANASONIC HOLDINGS CORPORATION
18.2.9
STMICROELECTRONICS
18.2.10
POLYMER SCIENCE, INC.
18.2.11
CARRAR
18.2.12
ZHENGZHOU KELIN MOTOR VEHICLE AIR CONDITIONING CO., LTD.
18.2.13
CALOGY SOLUTIONS
18.2.14
ZF FRIEDRICHSHAFEN AG
19
RESEARCH METHODOLOGY
343
19.1
RESEARCH DATA
19.1.1
SECONDARY DATA
19.1.1.1
LIST OF SECONDARY SOURCES
19.1.1.2
KEY DATA FROM SECONDARY SOURCES
19.1.2
PRIMARY DATA
19.1.2.1
OBJECTIVES OF PRIMARY RESEARCH
19.1.2.2
PRIMARY INTERVIEWS: DEMAND AND SUPPLY SIDES
19.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS
19.1.2.4
LIST OF PRIMARY PARTICIPANTS
19.2
MARKET SIZE ESTIMATION
19.2.1
BOTTOM-UP APPROACH
19.2.2
TOP-DOWN APPROACH
19.3
DATA TRIANGULATION
19.4
FACTOR ANALYSIS
19.4.1
DEMAND- AND SUPPLY-SIDE FACTOR ANALYSIS
19.4.2
REGIONAL ECONOMY IMPACT ANALYSIS
19.5
RESEARCH ASSUMPTIONS
19.6
RESEARCH LIMITATIONS
19.7
RISK ANALYSIS
20
APPENDIX
357
20.1
DISCUSSION GUIDE
20.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
20.3
CUSTOMIZATION OPTIONS
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE,
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY,
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COMPONENT,
COMPANY INFORMATION: PROFILING OF ADDITIONAL MARKET PLAYERS
20.4
RELATED REPORTS
20.5
AUTHOR DETAILS
LIST OF TABLES
TABLE 1
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY TECHNOLOGY
TABLE 2
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY BATTERY TYPE
TABLE 3
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY PROPULSION
TABLE 4
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY BATTERY CAPACITY
TABLE 5
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY VEHICLE TYPE
TABLE 6
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY OFFERING
TABLE 7
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DEFINITION, BY COMPONENT
TABLE 8
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: INCLUSIONS AND EXCLUSIONS
TABLE 9
USD EXCHANGE RATES, 2021–2025
TABLE 10
KEY COMPANY TECHNOLOGIES SUPPORTING TIGHTER CELL-LEVEL TEMPERATURE CONTROL IN HIGH-POWER-DENSITY BATTERIES
TABLE 11
KEY OEM AND EV PLATFORM TECHNOLOGIES SUPPORTING HIGH-POWER CHARGING
TABLE 12
PREDICTIVE THERMAL INTELLIGENCE AND EMERGING REVENUE OPPORTUNITIES
TABLE 13
OEM STRATEGIES TO BTMS AND BMS INTEGRATION
TABLE 14
IMPACT ANALYSIS OF MARKET DYNAMICS
TABLE 15
STRATEGIC MOVES BY OEMS AND TIER 1 & TIER 2/3 PLAYERS
TABLE 16
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2022–2031
TABLE 17
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS OFFERED BY KEY PLAYERS, BY PROPULSION, 2025 (USD)
TABLE 18
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY PROPULSION, 2023–2025 (USD)
TABLE 19
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY VEHICLE TYPE AND REGION, 2025 (USD)
TABLE 20
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: ROLE OF COMPANIES IN ECOSYSTEM
TABLE 21
OEM REQUIREMENTS FOR THERMAL UNIFORMITY & HEAT-FLUX MANAGEMENT
TABLE 22
OEM REQUIREMENTS FOR FAST CHARGING THERMAL MANAGEMENT
TABLE 23
OEM REQUIREMENTS FOR INTEGRATED VEHICLE THERMAL MANAGEMENT
TABLE 24
LIST OF FUNDING, 2023–2026
TABLE 25
IMPORT DATA FOR HS CODE 903289, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 26
EXPORT DATA FOR HS CODE 903289, BY COUNTRY, 2021–2025 (USD MILLION)
TABLE 27
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: KEY CONFERENCES AND EVENTS, 2026–2027
TABLE 28
OEM X EV BATTERY AND POWERTRAIN THERMAL INTEGRATION
TABLE 29
OEM X EV BATTERY AND CABIN THERMAL INTEGRATION
TABLE 30
OEM X BTMS PLATFORM STRATEGY
TABLE 31
OEM X TIER 1 TECHNOLOGY & SOURCING STRATEGY
TABLE 32
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: PATENT ANALYSIS, 2024–2026
TABLE 33
IMMERSION COOLING: COMPANY TECHNOLOGY STRATEGIES
TABLE 34
ARCHITECTURE COMPARISON, INTEGRATED VS. CONVENTIONAL THERMAL MANAGEMENT SYSTEMS
TABLE 35
BTMS ARCHITECTURE ROADMAP
TABLE 36
THERMAL MANAGEMENT TECHNOLOGY ROADMAP
TABLE 37
IMPORT TARIFFS ON BATTERY THERMAL MANAGEMENT SYSTEM MARKET AND KEY COMPONENTS IN INDIA
TABLE 38
IMPACT OF TRADE LIBERALIZATION ON BATTERY THERMAL MANAGEMENT SYSTEMS INTO INDIA
TABLE 39
IMPACT OF TRADE LIBERALIZATION ON BATTERY THERMAL MANAGEMENT SYSTEMS FROM INDIA
TABLE 40
KEY COUNTRY-LEVEL IMPACT OF 2026 IRAN CONFLICT ON BATTERY THERMAL MANAGEMENT SYSTEM MARKET
TABLE 41
TATA ELXSI ADOPTS AI-ENHANCED MULTIPHYSICS FRAMEWORK FOR PREDICTIVE BATTERY AND THERMAL MANAGEMENT IN ELECTRIC VEHICLES
TABLE 42
TESLA USES VEHICLE DATA AND ACTIVE THERMAL MANAGEMENT TO IMPROVE BATTERY SAFETY, DURABILITY, AND LONGEVITY
TABLE 43
IMPACT OF ECOSYSTEM PARTICIPANTS ON BATTERY THERMAL MANAGEMENT SYSTEM MARKET
TABLE 44
EUROPEAN UNION (EU): REGULATIONS AND INITIATIVES W.R.T. BATTERY THERMAL MANAGEMENT SYSTEMS
TABLE 45
INDIA: REGULATIONS AND INITIATIVES W.R.T. BATTERY THERMAL MANAGEMENT SYSTEMS
TABLE 46
CHINA: REGULATIONS AND INITIATIVES W.R.T. BATTERY THERMAL MANAGEMENT SYSTEMS
TABLE 47
CANADA: REGULATIONS AND INITIATIVES W.R.T. BATTERY THERMAL MANAGEMENT SYSTEMS
TABLE 48
US: REGULATIONS AND INITIATIVES W.R.T. BATTERY THERMAL MANAGEMENT SYSTEMS
TABLE 49
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 50
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 51
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 52
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY BTMS OFFERING (%)
TABLE 53
KEY BUYING CRITERIA FOR BATTERY THERMAL MANAGEMENT SYSTEMS, BY BTMS OFFERING
TABLE 54
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY, 2022–2025 (THOUSAND UNITS)
TABLE 55
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY, 2026–2033 (THOUSAND UNITS)
TABLE 56
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY, 2022–2025 (USD MILLION)
TABLE 57
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY, 2026–2033 (USD MILLION)
TABLE 58
ACTIVE SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 59
ACTIVE SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 60
ACTIVE SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 61
ACTIVE SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 62
HYBRID SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 63
HYBRID SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 64
HYBRID SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 65
HYBRID SYSTEMS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 66
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2022–2025 (THOUSAND UNITS)
TABLE 67
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2026–2033 (THOUSAND UNITS)
TABLE 68
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2022–2025 (USD MILLION)
TABLE 69
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2026–2033 (USD MILLION)
TABLE 70
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2022–2025 (THOUSAND UNITS)
TABLE 71
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2026–2033 (THOUSAND UNITS)
TABLE 72
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2022–2025 (USD MILLION)
TABLE 73
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE, 2026–2033 (USD MILLION)
TABLE 74
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 75
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 76
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 77
LITHIUM-ION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 78
LFP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 79
LFP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 80
LFP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 81
LFP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 82
NMC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 83
NMC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 84
NMC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 85
NMC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 86
LFMP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 87
LFMP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 88
LFMP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 89
LFMP: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 90
NCA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 91
NCA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 92
NCA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 93
NCA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 94
SOLID-STATE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 95
SOLID-STATE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 96
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE, 2022–2025 (THOUSAND UNITS)
TABLE 97
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE, 2026–2033 (THOUSAND UNITS)
TABLE 98
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE, 2022–2025 (USD MILLION)
TABLE 99
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE, 2026–2033 (USD MILLION)
TABLE 100
PASSENGER VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 101
PASSENGER VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 102
PASSENGER VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 103
PASSENGER VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 104
COMMERCIAL VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 105
COMMERCIAL VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 106
COMMERCIAL VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 107
COMMERCIAL VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 108
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY CAPACITY, 2022–2025 (THOUSAND UNITS)
TABLE 109
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY CAPACITY, 2026–2033 (THOUSAND UNITS)
TABLE 110
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY CAPACITY, 2022–2025 (USD MILLION)
TABLE 111
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY CAPACITY, 2026–2033 (USD MILLION)
TABLE 112
ELECTRIC VEHICLE MODELS, BY BATTERY CAPACITY, 2025-2026
TABLE 113
<50 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 114
<50 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 115
<50 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 116
<50 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 117
50-100 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 118
50-100 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 119
50-100 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 120
50-100 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 121
100-200 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 122
100-200 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 123
100-200 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 124
100-200 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 125
200-500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 126
200-500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 127
200-500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 128
200-500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 129
>500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 130
>500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 131
>500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 132
>500 KWH: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 133
BATTERY THERMAL MANAGEMENT MARKET, BY OFFERING, 2022–2025 (THOUSAND UNITS)
TABLE 134
BATTERY THERMAL MANAGEMENT MARKET, BY OFFERING, 2026–2033 (THOUSAND UNITS)
TABLE 135
BATTERY THERMAL MANAGEMENT MARKET, BY OFFERING, 2022–2025 (USD MILLION)
TABLE 136
BATTERY THERMAL MANAGEMENT MARKET, BY OFFERING, 2026–2033 (USD MILLION)
TABLE 137
BTMS WITH BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 138
BTMS WITH BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 139
BTMS WITH BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 140
BTMS WITH BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 141
BTMS WITHOUT BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 142
BTMS WITHOUT BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 143
BTMS WITHOUT BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 144
BTMS WITHOUT BATTERY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 145
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 146
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 147
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 148
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 149
BATTERY ELECTRIC VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 150
BATTERY ELECTRIC VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 151
BATTERY ELECTRIC VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 152
BATTERY ELECTRIC VEHICLE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 153
PLUG-IN HYBRID ELECTRIC VEHICLES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 154
PLUG-IN HYBRID ELECTRIC VEHICLES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 155
PLUG-IN HYBRID ELECTRIC VEHICLES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 156
PLUG-IN HYBRID ELECTRIC VEHICLES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 157
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COMPONENT, 2022–2025 (USD MILLION)
TABLE 158
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COMPONENT, 2026–2033 (USD MILLION)
TABLE 159
THERMAL SENSORS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 160
THERMAL SENSORS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 161
COOLING PLATES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 162
COOLING PLATES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 163
HEAT PIPES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 164
HEAT PIPES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 165
PUMPS/FANS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 166
PUMPS/FANS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 167
BATTERY CHILLERS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 168
BATTERY CHILLERS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 169
HEAT EXCHANGERS/RADIATORS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 170
HEAT EXCHANGERS/RADIATORS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 171
VALVES/EXPANSION VALVES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 172
VALVES/EXPANSION VALVES: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 173
REFRIGERANT CIRCUIT HARDWARE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 174
REFRIGERANT CIRCUIT HARDWARE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 175
COOLANT CIRCUITS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 176
COOLANT CIRCUITS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 177
BATTERY HEATERS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 178
BATTERY HEATERS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 179
BTMS CONTROLLERS & WIRING: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 180
BTMS CONTROLLERS & WIRING: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 181
TIM & INSULATION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 182
TIM & INSULATION: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 183
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (THOUSAND UNITS)
TABLE 184
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (THOUSAND UNITS)
TABLE 185
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 186
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 187
ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)
TABLE 188
ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)
TABLE 189
ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 190
ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 191
CHINA: LIST OF OEM MODELS WITH BATTERY THERMAL MANAGEMENT SYSTEMS, 2025–2026
TABLE 192
CHINA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 193
CHINA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 194
CHINA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 195
CHINA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 196
INDIA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 197
INDIA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 198
INDIA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 199
INDIA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 200
JAPAN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 201
JAPAN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 202
JAPAN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 203
JAPAN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 204
SOUTH KOREA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 205
SOUTH KOREA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 206
SOUTH KOREA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 207
SOUTH KOREA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 208
REST OF ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 209
REST OF ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 210
REST OF ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 211
REST OF ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 212
EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)
TABLE 213
EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)
TABLE 214
EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 215
EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 216
FRANCE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 217
FRANCE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 218
FRANCE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 219
FRANCE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 220
GERMANY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 221
GERMANY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 222
GERMANY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 223
GERMANY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 224
NORWAY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 225
NORWAY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 226
NORWAY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 227
NORWAY: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 228
UK: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 229
UK: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 230
UK: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 231
UK: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 232
SWEDEN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 233
SWEDEN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 234
SWEDEN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 235
SWEDEN: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 236
NETHERLANDS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 237
NETHERLANDS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 238
NETHERLANDS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 239
NETHERLANDS: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 240
REST OF EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 241
REST OF EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 242
REST OF EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 243
REST OF EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 244
NORTH AMERICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)
TABLE 245
NORTH AMERICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)
TABLE 246
NORTH AMERICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 247
NORTH AMERICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 248
US: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 249
US: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 250
US: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 251
US: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 252
CANADA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 253
CANADA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 254
CANADA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 255
CANADA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 256
REST OF THE WORLD: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (THOUSAND UNITS)
TABLE 257
REST OF THE WORLD: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (THOUSAND UNITS)
TABLE 258
REST OF THE WORLD: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 259
REST OF THE WORLD: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 260
UAE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 261
UAE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 262
UAE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 263
UAE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 264
EGYPT: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 265
EGYPT: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 266
EGYPT: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 267
EGYPT: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 268
SOUTH AFRICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (THOUSAND UNITS)
TABLE 269
SOUTH AFRICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (THOUSAND UNITS)
TABLE 270
SOUTH AFRICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 271
SOUTH AFRICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 272
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: KEY PLAYER STRATEGIES/ RIGHT TO WIN, JANUARY 2024–SEPTEMBER 2026
TABLE 273
MARKET SHARE ANALYSIS, 2025
TABLE 274
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: REGION FOOTPRINT
TABLE 275
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: TECHNOLOGY FOOTPRINT
TABLE 276
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: BATTERY TYPE FOOTPRINT
TABLE 277
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: VEHICLE TYPE FOOTPRINT
TABLE 278
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: PROPULSION FOOTPRINT
TABLE 279
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: LIST OF KEY STARTUPS/SMES
TABLE 280
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: COMPETITIVE BENCHMARKING OF STARTUPS/SMES
TABLE 281
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: PRODUCT LAUNCHES AND DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
TABLE 282
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: DEALS, JANUARY 2024-SEPTEMBER 2026
TABLE 283
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: EXPANSIONS, JANUARY 2024-SEPTEMBER 2026
TABLE 284
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: OTHER DEVELOPMENTS, JANUARY 2024-SEPTEMBER 2026
TABLE 285
ROBERT BOSCH GMBH: COMPANY OVERVIEW
TABLE 286
ROBERT BOSCH GMBH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 287
ROBERT BOSCH GMBH: DEALS
TABLE 288
ROBERT BOSCH GMBH: OTHER DEVELOPMENTS
TABLE 289
GENTHERM: COMPANY OVERVIEW
TABLE 290
GENTHERM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 291
GENTHERM: DEALS
TABLE 292
VALEO: COMPANY OVERVIEW
TABLE 293
VALEO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 294
VALEO: PRODUCT LAUNCHES AND DEVELOPMENTS
TABLE 295
VALEO: DEALS
TABLE 296
VALEO: EXPANSIONS
TABLE 297
VALEO: OTHER DEVELOPMENTS
TABLE 298
AUMOVIO: COMPANY OVERVIEW
TABLE 299
AUMOVIO: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 300
AUMOVIO: OTHER DEVELOPMENTS
TABLE 301
DENSO CORPORATION: COMPANY OVERVIEW
TABLE 302
DENSO CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 303
DENSO CORPORATION: PRODUCT DEVELOPMENTS
TABLE 304
DENSO CORPORATION: DEALS
TABLE 305
DENSO CORPORATION: OTHER DEVELOPMENTS
TABLE 306
MAHLE GMBH: COMPANY OVERVIEW
TABLE 307
MAHLE GMBH: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 308
MAHLE GMBH: PRODUCT LAUNCHES
TABLE 309
MAHLE GMBH: DEALS
TABLE 310
MAHLE GMBH: EXPANSIONS
TABLE 311
MAHLE GMBH: OTHER DEVELOPMENTS
TABLE 312
BORGWARNER INC.: COMPANY OVERVIEW
TABLE 313
BORGWARNER INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 314
BORGWARNER INC.: PRODUCT LAUNCHES AND DEVELOPMENTS
TABLE 315
BORGWARNER INC.: DEALS
TABLE 316
BORGWARNER INC.: EXPANSIONS
TABLE 317
BORGWARNER INC.: OTHER DEVELOPMENTS
TABLE 318
DANA LIMITED: COMPANY OVERVIEW
TABLE 319
DANA LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 320
DANA LIMITED: EXPANSIONS
TABLE 321
DANA LIMITED: OTHER DEVELOPMENTS
TABLE 322
GRAYSON THERMAL SYSTEMS: COMPANY OVERVIEW
TABLE 323
GRAYSON THERMAL SYSTEMS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 324
GRAYSON THERMAL SYSTEMS: PRODUCT LAUNCHES
TABLE 325
GRAYSON THERMAL SYSTEMS: EXPANSIONS
TABLE 326
WEBASTO GROUP: COMPANY OVERVIEW
TABLE 327
WEBASTO GROUP: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 328
WEBASTO GROUP: PRODUCT LAUNCHES
TABLE 329
WEBASTO GROUP: OTHER DEVELOPMENTS
TABLE 330
LG CHEM: COMPANY OVERVIEW
TABLE 331
LG CHEM: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 332
LG CHEM: PRODUCT DEVELOPMENTS
TABLE 333
LG CHEM: DEALS
TABLE 334
LG CHEM: OTHER DEVELOPMENTS
TABLE 335
HANON SYSTEMS: COMPANY OVERVIEW
TABLE 336
HANON SYSTEMS: PRODUCTS/SOLUTIONS/SERVICES OFFERED
TABLE 337
HANON SYSTEMS: EXPANSIONS
TABLE 338
HANON SYSTEMS: OTHER DEVELOPMENTS
TABLE 339
VOSS: COMPANY OVERVIEW
TABLE 340
MARELLI HOLDINGS CO., LTD.: COMPANY OVERVIEW
TABLE 341
LEM INTERNATIONAL SA: COMPANY OVERVIEW
TABLE 342
ORION BMS: COMPANY OVERVIEW
TABLE 343
RENESAS ELECTRONICS CORPORATION: COMPANY OVERVIEW
TABLE 344
3M: COMPANY OVERVIEW
TABLE 345
INFINEON TECHNOLOGIES AG: COMPANY OVERVIEW
TABLE 346
PANASONIC HOLDINGS CORPORATION: COMPANY OVERVIEW
TABLE 347
STMICROELECTRONICS: COMPANY OVERVIEW
TABLE 348
POLYMER SCIENCE, INC.: COMPANY OVERVIEW
TABLE 349
CARRAR: COMPANY OVERVIEW
TABLE 350
ZHENGZHOU KELIN MOTOR VEHICLE AIR CONDITIONING CO., LTD.: COMPANY OVERVIEW
TABLE 351
CALOGY SOLUTIONS: COMPANY OVERVIEW
TABLE 352
ZF FRIEDRICHSHAFEN AG: COMPANY OVERVIEW
TABLE 353
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: RISK ANALYSIS
LIST OF FIGURES
FIGURE 1
MARKETS SEGMENTATION AND REGIONAL SNAPSHOT
FIGURE 2
YEARS CONSIDERED
FIGURE 3
BATTERY THERMAL MANAGEMENT SYSTEM MARKET SHOWING STEADY GROWTH, 2022-2033
FIGURE 4
BATTERY THERMAL MANAGEMENT SYSTEM MARKET DYNAMICS
FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN BATTERY THERMAL MANAGEMENT SYSTEM MARKET
FIGURE 6
DISRUPTIVE TRENDS IMPACTING GROWTH OF BATTERY THERMAL MANAGEMENT SYSTEM MARKET
FIGURE 7
COMMERCIAL VEHICLE AND HYBRID TECHNOLOGY SEGMENTS TO ACHIEVE SIGNIFICANT GROWTH IN 2026–2033
FIGURE 8
ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD
FIGURE 9
ADVANCEMENTS IN BATTERY TECHNOLOGIES AND EV ADOPTION TO ACCELERATE BTMS MARKET GROWTH
FIGURE 10
BATTERY ELECTRIC VEHICLE SEGMENT TO REGISTER HIGHER CAGR DUE TO RISING BATTERY CAPACITY
FIGURE 11
PASSENGER VEHICLE SEGMENT TO DOMINATE MARKET DURING FORECAST PERIOD DUE TO HIGH EV ADOPTION
FIGURE 12
LITHIUM-ION BATTERIES TO GROW AT HIGHER CAGR DUE TO HIGHER ENERGY DENSITY REQUIREMENTS
FIGURE 13
ACTIVE SYSTEMS TO COMMAND DOMINANT MARKET SHARE DUE TO FLEXIBLE POWERTRAIN CONFIGURATIONS
FIGURE 14
50-100 KWH SEGMENT TO DOMINATE MARKET FROM 2026 TO 2033 DUE TO HIGHER ADOPTION IN PASSENGER EVS
FIGURE 15
COOLING PLATES TO BE LARGEST SEGMENT DUE TO HIGH ADOPTION IN LIQUID COOLED BTMS FOR EFFECTIVE BATTERY HEAT REMOVAL
FIGURE 16
BTMS WITH BATTERY SEGMENT TO BE FASTER-GROWING MARKET DUE TO INCREASING INTEGRATION OF BTMS COMPONENTS WITH BATTERY PACKS
FIGURE 17
ASIA PACIFIC TO ACCOUNT FOR LARGEST MARKET SHARE IN
FIGURE 18
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
FIGURE 19
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY PROPULSION, 2023–2025 (USD)
FIGURE 20
AVERAGE SELLING PRICE TREND OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY VEHICLE TYPE AND REGION, 2025 (USD)
FIGURE 21
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: ECOSYSTEM ANALYSIS
FIGURE 22
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: VALUE CHAIN ANALYSIS
FIGURE 23
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: INVESTMENT AND FUNDING SCENARIO, 2023–2026
FIGURE 24
IMPORT DATA FOR HS CODE 903289, BY COUNTRY, 2021–2025 (USD MILLION)
FIGURE 25
EXPORT DATA FOR HS CODE 903289, BY COUNTRY, 2021–2025 (USD MILLION)
FIGURE 26
TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
FIGURE 27
BILL OF MATERIALS, BEV VS. PHEV, 2026
FIGURE 28
BTMS BATTERY ARCHITECTURE EVOLUTION
FIGURE 29
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: PATENT ANALYSIS, 2016–2026
FIGURE 30
PHASE CHANGE MATERIALS IN BATTERY THERMAL MANAGEMENT
FIGURE 31
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS OF BATTERY THERMAL MANAGEMENT SYSTEMS, BY BTMS OFFERING
FIGURE 32
KEY BUYING CRITERIA FOR BATTERY THERMAL MANAGEMENT SYSTEMS, BY BTMS OFFERING
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY TECHNOLOGY,
2026
VS. 2033 (USD MILLION)
140
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY TYPE,
2026
VS. 2033 (USD MILLION)
151
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY VEHICLE TYPE,
2026
VS. 2033 (USD MILLION)
166
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY BATTERY CAPACITY,
2026
VS. 2033 (USD MILLION)
173
BATTERY THERMAL MANAGEMENT MARKET, BY OFFERING,
2026
VS. 2033 (USD MILLION)
187
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY PROPULSION,
2026
VS. 2033 (USD MILLION)
194
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY COMPONENT,
2026
VS. 2033 (USD MILLION)
202
BATTERY THERMAL MANAGEMENT SYSTEM MARKET, BY REGION,
2026
VS. 2033 (USD MILLION)
221
FIGURE 41
ASIA PACIFIC: BATTERY THERMAL MANAGEMENT SYSTEM MARKET SNAPSHOT
EUROPE: BATTERY THERMAL MANAGEMENT SYSTEM MARKET,
2026
VS. 2033 (USD MILLION)
235
FIGURE 43
NORTH AMERICA: BATTERY THERMAL MANAGEMENT SYSTEM MARKET SNAPSHOT
REST OF THE WORLD: BATTERY THERMAL MANAGEMENT SYSTEM MARKET,
2026
VS. 2033 (USD MILLION)
255
FIGURE 45
REVENUE ANALYSIS OF KEY PLAYERS IN BATTERY THERMAL MANAGEMENT SYSTEM MARKET, 2021–2025
FIGURE 46
MARKET SHARE OF KEY PLAYERS IN BATTERY THERMAL MANAGEMENT SYSTEM MARKET, 2025
FIGURE 47
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025
FIGURE 48
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: COMPANY FOOTPRINT
FIGURE 49
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025
FIGURE 50
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: COMPANY VALUATION OF TOP 5 PLAYERS
FIGURE 51
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: EV/EBITDA OF TOP 5 PLAYERS
FIGURE 52
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: BRAND/PRODUCT COMPARATIVE ANALYSIS
FIGURE 53
ROBERT BOSCH GMBH: COMPANY SNAPSHOT
FIGURE 54
GENTHERM: COMPANY SNAPSHOT
FIGURE 55
VALEO: COMPANY SNAPSHOT
FIGURE 56
AUMOVIO: COMPANY SNAPSHOT
FIGURE 57
DENSO CORPORATION: COMPANY SNAPSHOT
FIGURE 58
MAHLE GMBH: COMPANY SNAPSHOT
FIGURE 59
BORGWARNER INC.: COMPANY SNAPSHOT
FIGURE 60
DANA LIMITED: COMPANY SNAPSHOT
FIGURE 61
LG CHEM: COMPANY SNAPSHOT
FIGURE 62
HANON SYSTEMS: COMPANY SNAPSHOT
FIGURE 63
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: RESEARCH DESIGN
FIGURE 64
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: RESEARCH DESIGN MODEL
FIGURE 65
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: RESEARCH METHODOLOGY
FIGURE 66
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: BOTTOM-UP APPROACH
FIGURE 67
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: TOP-DOWN APPROACH
FIGURE 68
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: DATA TRIANGULATION
FIGURE 69
BATTERY THERMAL MANAGEMENT SYSTEM MARKET: GROWTH PROJECTIONS FROM DEMAND-SIDE DRIVERS
The research study involved extensive secondary sources, such as company annual reports/presentations, industry association publications, magazine articles, directories, technical handbooks, World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the battery thermal management system (BTMS) market. Primary sources, such as experts from related industries, automobile OEMs, and suppliers, were interviewed to obtain and verify critical information and assess the growth prospects and market estimations.
Secondary ResearchSecondary sources for this research study include corporate filings, such as annual reports, investor presentations, and financial statements; trade, business, and professional associations; whitepapers, MarkLines, and the OICA (International Organization of Motor Vehicle Manufacturers); certified publications; articles by recognized authors; directories; and databases. Secondary data was collected and analyzed to determine the overall market size, further validated by primary research.
Primary ResearchExtensive primary research was conducted after understanding the BTMS market scenario through secondary research. Several primary interviews were conducted with market experts from the demand side (vehicle manufacturers, country-level government associations, and trade associations) and the supply side (BTMS manufacturers, component providers, and system integrators). The regions considered for the research include North America, Europe, Asia Pacific, and the Rest of the World. Approximately 17% and 83% of primary interviews were conducted from the demand and supply sides. Primary data was collected through questionnaires, emails, and telephonic interviews. In the canvassing of primary data, various departments within organizations, such as sales, operations, and marketing, were covered to provide a holistic viewpoint in this report.
After interacting with industry experts, brief sessions were conducted with highly experienced independent consultants to reinforce the findings from the primaries. This, along with the in-house subject matter experts’ opinions, led to the findings described in this report.

Note: Tiers of companies are based on the value chain of the BTMS market; companies’ revenues were not considered.
To know about the assumptions considered for the study, download the pdf brochure
A detailed market estimation approach was followed to estimate and validate the volume and value of the BTMS market and other submarkets, as mentioned below.

After arriving at the overall market size through the aforementioned methodology, the BTMS market was split into several segments and subsegments. The data triangulation procedure was employed, wherever applicable, to complete the overall market engineering process and arrive at the exact market value for key segments and subsegments. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the demand- and supply-side participants.
According to Grayson Thermal Systems, BTMS encompasses technologies and solutions that help regulate and control the temperature of batteries in electric vehicles, specifically battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), and fuel cell electric vehicles (FCEVs). These systems help maintain optimal battery performance, range, and service life by ensuring that batteries operate within a specified temperature range. BTMS includes various components such as cooling systems, heating systems, insulation materials, sensors, and control algorithms to efficiently manage battery temperatures under different operating conditions.
With the given market data, MarketsandMarkets offers customizations in accordance with the company’s specific needs.
COMPANY INFORMATION:


PRODUCT DIRECTOR, WEASLER
Global Provider of Industrial Actuation & Control Solutions
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Vice President
A global technology company that develops safer, greener and more connected solutions.
We contracted with MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our interest in the Fleet Management space. The team successfully completed the work on time and at the pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with us to help us get the visibility we needed to make an investment.
We have subsequently used MarketsandMarkets again related to Smart Cities to good results.