Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASA
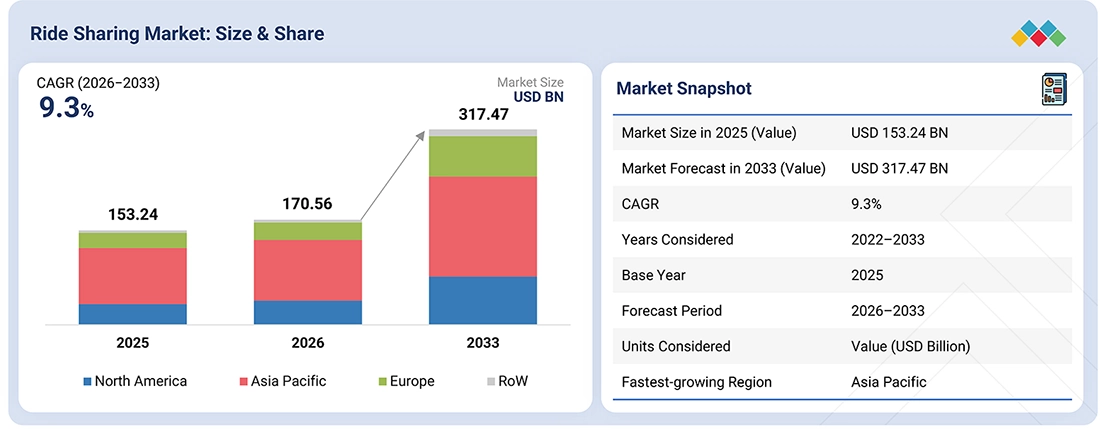
USD 317.47 BN
MARKET SIZE, 2033

CAGR 9.3%
(2026-2033)

340
REPORT PAGES

200
MARKET TABLES
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global ride sharing market size is estimated at USD 170.56 billion in 2026 and is projected to reach USD 317.47 billion by 2033, at a CAGR of 9.3%, during the forecast period (2026-2033). The market is expected to grow as platforms increasingly evolve from basic ride matching into AI-driven mobility orchestration, using real-time demand prediction, dynamic pricing, driver positioning, and multi-modal trip optimization to improve vehicle utilization and reduce empty miles. Integration with public transit, corporate mobility, airports, and micro-mobility is expanding the addressable use case, allowing platforms to manage complete journeys rather than individual rides. Meanwhile, EV adoption within ride-hailing fleets is encouraging higher fleet utilization through optimized charging, vehicle assignment, and energy-aware dispatch algorithms, creating opportunities for lower operating costs and fleet-level energy management. Increasing availability of connected-vehicle data and APIs is also enabling predictive maintenance, driver-risk analytics, automated incident detection, and personalized fleet operations. Higher utilization increases pressure on driver economics, vehicle depreciation, charging/uptime management, and platform incentives, while fragmented regulations and data-sharing requirements across cities can make it difficult for operators to scale a standardized technology and business model.
RIDE SHARING MARKET, BY REGION
Asia Pacific leads the regional ride sharing market, contributing to >55% in 2026. North America is the second-largest market followed by Europe and the Rest of the World
BY SERVICE TYPE
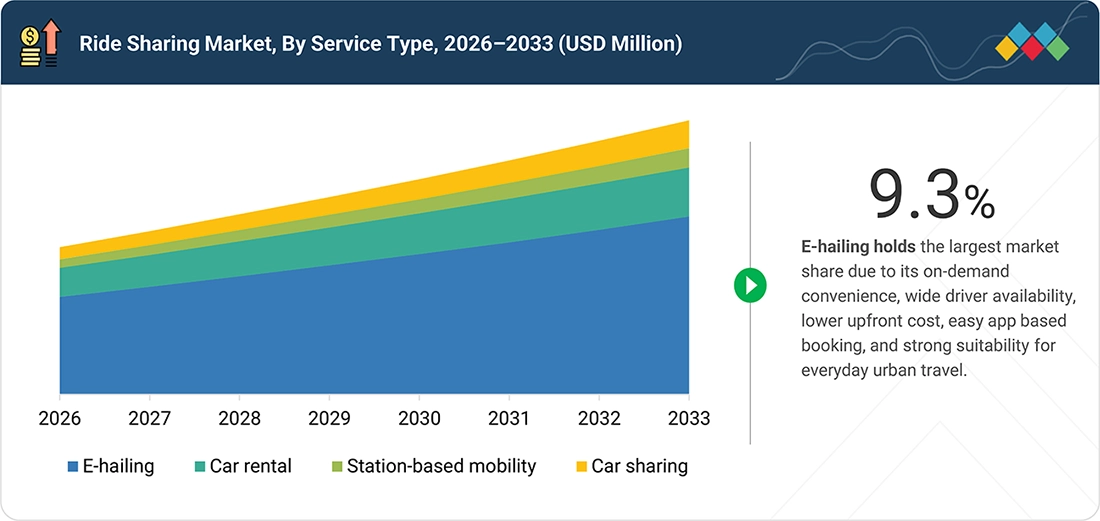
Car sharing is expected to register the fastest growth of 12.7% by value in the ride sharing market during the forecast period.
BY VEHICLE TYPE
Hatchback/sedan is expected to dominate the ride sharing market, by vehicle type in 2026.
BY BUSINESS MODEL
B2B/corporate is expected to register the fastest growth of 10.6% by value in the ride sharing market during the forecast period.
BY PROPULSION
CNG/petrol is expected to dominate the ride sharing market in 2026 due to the large existing fleet base, established refueling network, and lower fleet transition costs.
BY DATA SERVICE
Navigation is expected to dominate the ride sharing market in 2026 due to continuous reliance on GPS, mapping, traffic data, and route optimization for ride matching and trip management.
COMPETITIVE LANDSCAPE
Major market players have adopted both organic and inorganic strategies, including partnerships and investments. Key players include Uber Technologies, Inc. (US), DiDi Global Inc. (China), Lyft, Inc. (US), Grab (Singapore), and Bolt (Estonia). Micro mobility players are expanding their presence in the ride sharing market through platform integration, fleet expansion, and partnerships with mobility operators. Key players include Lime (California), Bird (Florida), and Lyft, Inc. (US).
Ride sharing has evolved from an app-based taxi service into a technology-enabled mobility system that integrates passengers, drivers, vehicles, payments, mapping, and fleet operations through digital platforms. Real-time demand and supply matching, GPS-based tracking, dynamic pricing, route optimization, and digital payments enable platforms to improve vehicle utilization while reducing passenger waiting time. Future growth is expected to depend on autonomous vehicles, electric fleets, advanced fleet management, and deeper integration with public transportation networks. Autonomous driving can fundamentally change the supply structure by reducing dependence on human drivers and enabling platforms to coordinate vehicles based on demand, charging requirements, maintenance schedules, and utilization levels.
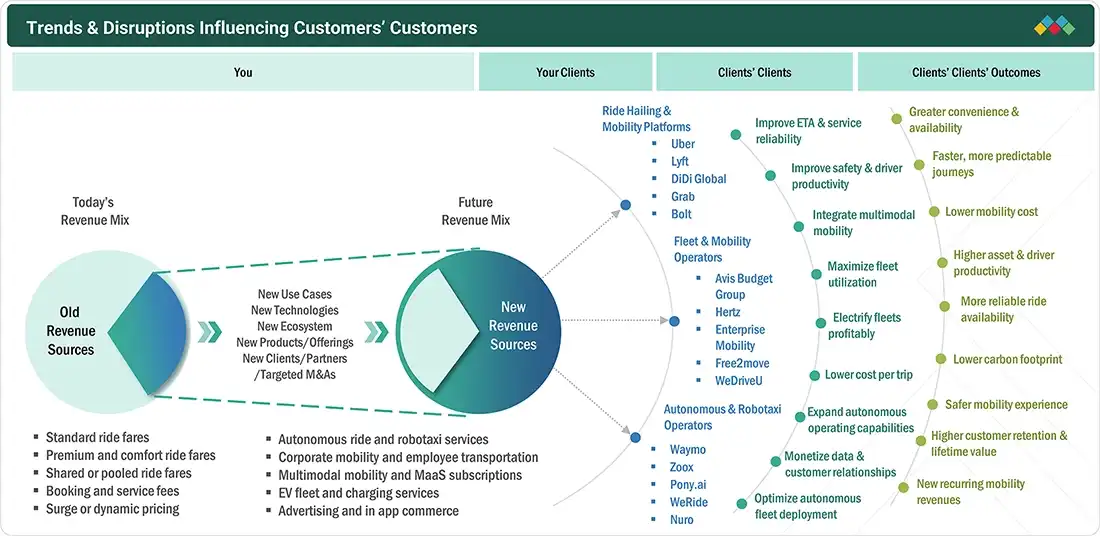
The future revenue opportunity in ride sharing is expected to increasingly shift toward new mobility products and value-added services, rather than remaining dependent on traditional point-to-point rides. To capture this opportunity, service providers will focus on client imperatives such as maximizing fleet utilization, lowering cost per trip, improving service reliability, enabling profitable fleet electrification, integrating multimodal mobility, and monetizing data and customer relationships. These imperatives ultimately translate into client outcomes including higher asset productivity, lower mobility costs, more predictable and convenient journeys, improved safety, greater customer retention, and new recurring revenue streams. This creates a clear value chain from new products and services → provider capabilities → client imperatives → measurable end-customer outcomes.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Drivers
Impact
Level


RESTRAINTS
Impact
Level


OPPORTUNITIES
Impact
Level


CHALLENGES
Impact
Level


Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The rising cost and complexity of owning a private vehicle are encouraging consumers to separate mobility access from asset ownership. A vehicle creates financial commitments even when it is parked or used infrequently, while expenses such as depreciation, insurance, maintenance, repairs, fuel, and parking continue to accumulate. This makes ownership less economically attractive for consumers who do not require daily private vehicle access. Ride sharing addresses this gap by converting mobility from an ownership-based expense into a usage-based service, allowing customers to pay only when transportation is required.
Ride sharing platforms have historically benefited from an asset-light marketplace structure in which the platform connects riders with independently operating drivers, while limiting direct exposure to employment costs and fleet ownership. Regulatory intervention is challenging this structure by increasing requirements around driver earnings, worker protections, insurance, taxation, safety, and employment classification. As governments move toward stronger protections for platform workers, the cost advantage of the decentralized driver model can narrow because platforms may need to provide minimum earnings, healthcare or other benefits, occupational protection, paid leave, or collective bargaining mechanisms. This puts pressure on the historically variable cost structure of ride sharing, particularly in markets where driver payments represent a significant component of the cost of fulfilling each trip.
Autonomous vehicles can enable new trip occasions that are constrained by driver availability, operating hours, safety considerations, and trip economics. Autonomous services can potentially operate continuously without dependence on individual driver working hours, allowing platforms to serve late night, early morning, and other periods with limited driver supply. This can bring previously underserved trips into the addressable market, including essential commuting, business travel, healthcare-related mobility, and other time-sensitive journeys. Early commercial deployment data also indicates that autonomous services are generating recurring trips rather than functioning only as substitutes for existing human-driven rides, supporting the view that AVs can add incremental demand to the ride sharing ecosystem.
Ride sharing platforms face a structural tradeoff between keeping fares affordable for riders, providing sufficient earnings to drivers, and retaining enough revenue to cover platform operating costs and generate sustainable margins. These three requirements are closely connected because changes in one area can directly affect the others. Lower fares can stimulate bookings but reduce the amount available for drivers and the platform. Higher driver earnings can improve driver retention and availability but raise the cost of fulfilling each trip. Higher platform fees or fares can protect margins but may reduce rider demand or make the service less competitive with other mobility options.
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
|
|
Uber enables on-demand, shared rides through options such as UberX and UberX Share, with upfront pricing, driver matching, GPS tracking, trip sharing, and in-app safety tools. UberX Share matches riders travelling in a similar direction with another rider to reduce the cost of the trip. | Enables convenient and cost-efficient urban mobility while improving price transparency and ride safety. Shared rides can reduce the cost per passenger and help reduce additional vehicle travel. |
|
|
DiDi provides app-based ride-hailing through services such as DiDi Express, which matches riders with nearby drivers. The platform uses trip time and distance to calculate fares and provides in-app safety features and 24-hour support for riders. | Provides accessible and affordable point-to-point mobility while improving driver availability and rider safety through digital matching, trip monitoring, and in-app safety support. |
|
|
Lyft provides on-demand and scheduled rides through multiple ride types, including Standard, Wait & Save, Priority Pickup, Extra Comfort, Black, and XL. Its platform allows riders to select services based on price, pickup speed, vehicle type, and passenger capacity. | Enables riders to select rides according to urgency, budget, comfort, and group size, while expanding ride sharing access across everyday commuting and scheduled travel needs. |
|
|
Grab provides app-based private car and taxi rides through services such as GrabCar and JustGrab. JustGrab automatically assigns the nearest available car or taxi and provides an upfront fare before booking, while GrabCar allows riders to request private rides and track the assigned driver and vehicle. | Improves ride availability and pickup convenience by matching riders with nearby vehicles, while upfront pricing provides greater fare transparency and trip tracking supports safer journeys. |
|
|
Bolt enables app-based car rides with features, including driver and vehicle verification, GPS-tracked trips, ride sharing of trip details, Emergency Assist, pickup codes, and Ride Check for detecting unexpected stops during a journey. | Strengthens rider confidence through identity and vehicle verification, real-time trip monitoring, emergency assistance, and privacy controls, supporting safer and more reliable ride hailing. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
The ride sharing market operates through an interconnected ecosystem of mobility platforms, drivers, vehicle owners, passengers, fleet operators, vehicle manufacturers, payment and financial service providers, and technology and infrastructure providers. Mobility platforms coordinate demand and supply through digital applications, dynamic pricing, dispatch, driver matching, and payment systems, while drivers, vehicle owners, and fleet operators provide the physical mobility capacity. OEMs and vehicle technology providers influence the ecosystem through connected vehicles, electrification, fleet-specific vehicles, and driver assistance technologies. Payment providers, mapping and navigation companies, telecommunications networks, and cloud technology providers support transaction processing, route optimization, connectivity, and platform operations. Regulatory authorities and transport agencies establish requirements for licensing, safety, insurance, data handling, and commercial vehicle operations, making regulatory compliance an important link across the ecosystem.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Car sharing is expected to grow at the fastest rate as consumers increasingly seek access to vehicles without the costs of ownership, while app-based booking, flexible rental durations, and expanding vehicle availability make shared cars more practical for urban and occasional travel.
Hatchbacks/sedans are expected to hold the largest share due to their widespread availability, lower operating and acquisition costs, fuel efficiency, and suitability for everyday urban trips, making them economical for both drivers and riders.
B2B and corporate ride sharing is expected to grow at the fastest rate as businesses increasingly use managed mobility services for employee commuting, business travel, and airport transfers, while centralized billing, predictable costs, and easier trip management improve operational efficiency.
CNG/petrol vehicles are expected to dominate due to their larger installed vehicle base, established refueling infrastructure, lower fleet transition requirements, and suitability for high-utilization ride sharing operations, particularly in markets where EV charging networks are still developing.
Navigation is expected to dominate data services as ride sharing platforms rely continuously on mapping, GPS, traffic data, route optimization, and real-time location tracking to match riders and drivers, optimize trips, and improve pickup accuracy.
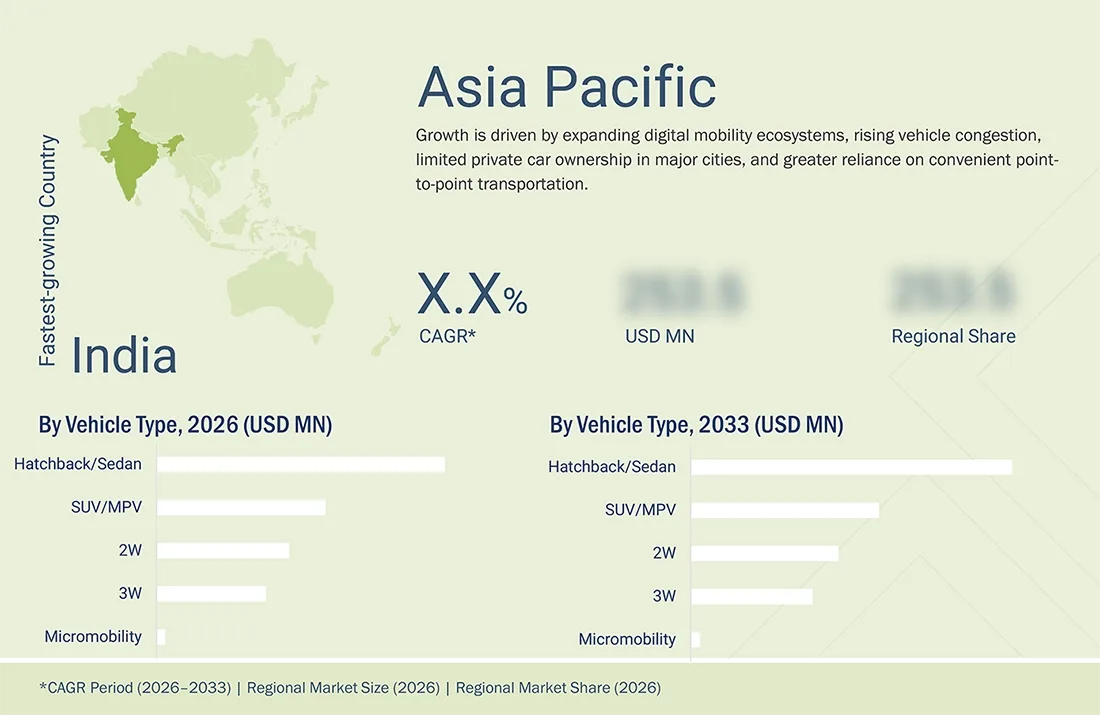
Asia Pacific is the largest ride sharing market due to the strong presence of two-wheeler and three-wheeler-based mobility, which expands ride sharing beyond conventional cars and supports shorter, frequent trips. Integration of ride sharing with public transport networks is also improving first- and last-mile connectivity, while corporate employee transport programs and airport mobility are creating additional recurring demand. The region is further supported by the rapid electrification of shared fleets and expansion of intercity mobility services, broadening the use of ride sharing across different trip purposes.
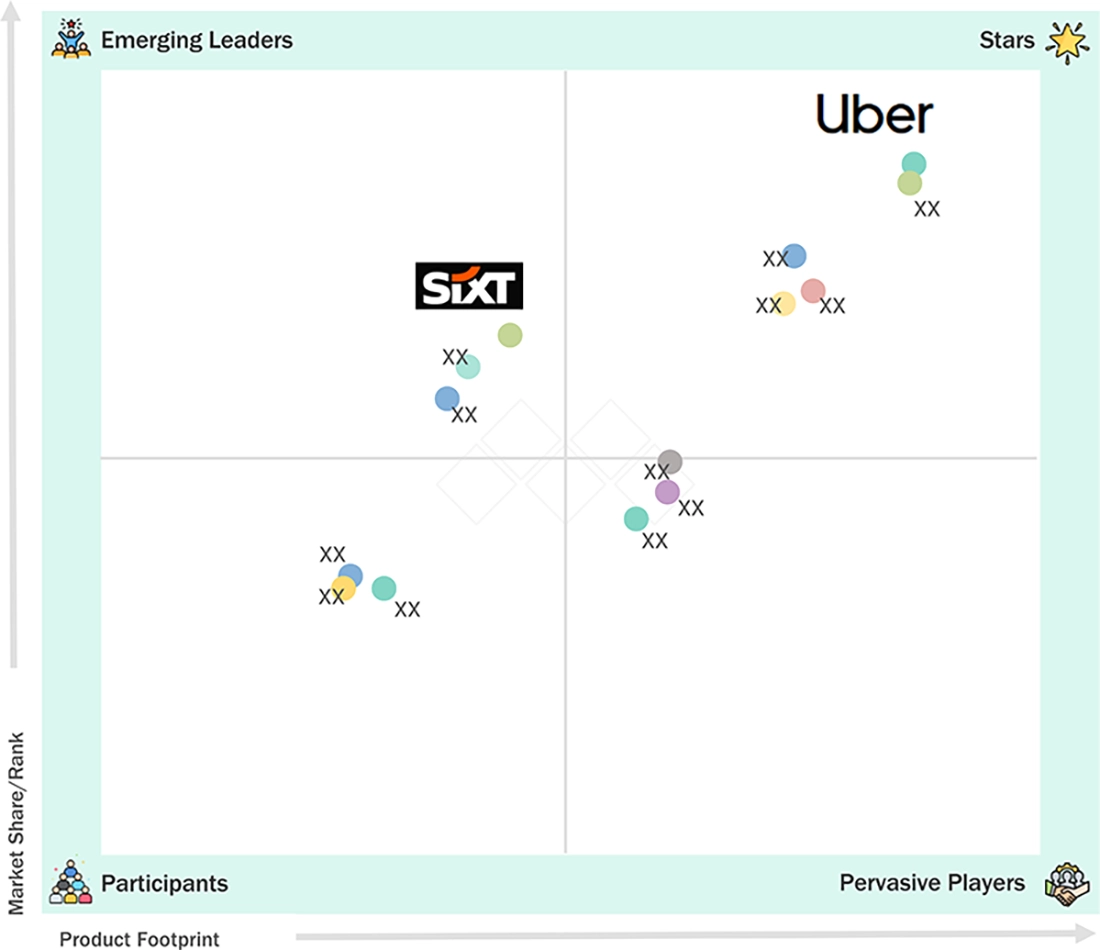
In the ride sharing market, Uber Technologies, Inc. (Star) focuses on app-based ride hailing, offering on-demand and shared rides across multiple markets while expanding its mobility platform through diverse ride options and technology-enabled services. Sixt SE (Emerging) focuses on digitally enabled car rental and shared mobility services, combining flexible vehicle access, app-based booking, and an expanding fleet to serve individual and business mobility requirements.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 153.24 Billion |
| Market Forecast in 2033 (Value) | USD 317.47 Billion |
| Growth Rate | CAGR of 9.3% from 2026-2033 |
| Years Considered | 2022-2033 |
| Base Year | 2025 |
| Forecast Period | 2026-2033 |
| Units Considered | Value (USD Million) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered | Service type, business model, vehicle type, propulsion, data service, and distance |
| Regions Covered | Asia Pacific, Europe, North America, and Rest of the World |
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Benchmark leading ridesharing platforms and their service offerings | Benchmarked leading platforms across e-hailing, car sharing, car rental, and station-based mobility, covering service availability, booking models, pricing approaches, safety features, and geographic presence | Identifies competitive gaps and helps clients assess opportunities for service expansion and differentiation |
| Assess the impact of EV adoption on ridesharing fleets | Evaluated EV adoption across major ridesharing markets, including fleet transition, charging availability, operating economics, and platform initiatives supporting electric mobility | Supports fleet transition planning by highlighting market readiness, infrastructure requirements, and potential operating benefits |
| Identify opportunities in corporate and business mobility | Assessed B2B and corporate ridesharing applications, including employee transportation, business travel, airport transfers, centralized billing, and managed mobility programs | Helps identify recurring demand opportunities and potential revenue streams beyond individual consumers |
| Evaluate regulatory developments affecting ridesharing operations | Assessed country and city-level requirements covering driver licensing, vehicle permits, platform regulations, safety requirements, pricing restrictions, and employment related measures | Helps clients anticipate regulatory changes and assess their potential impact on platform operations, driver supply, and costs |
| Identify emerging technology opportunities in ridesharing | Evaluated adoption of autonomous vehicles, connected fleet data, AI-based matching, route optimization, digital payments, and real-time safety technologies across leading platforms | Highlights technology opportunities that can improve fleet utilization, customer experience, safety, and long-term platform economics |
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
26
2
EXECUTIVE SUMMARY
32
3
PREMIUM INSIGHTS
37
4
MARKET OVERVIEW
Multimodal integration and autonomous tech redefine ride-sharing, expanding market potential beyond urban centers.41
4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
TAM EXPANSION VIA MULTIMODAL INTEGRATION
4.2.1.2
GROWING PREFERENCE FOR SHARED TRANSPORTATION
4.2.2
RESTRAINTS
4.2.2.1
REGULATORY INTERVENTION IN PLATFORM ECONOMICS
4.2.3
OPPORTUNITIES
4.2.3.1
AUTONOMOUS VEHICLES EXPANDING DEMAND BEYOND TRADITIONAL RIDE SHARING USE CASES
4.2.3.2
MONETIZATION OF CONNECTED FLEET DATA
4.2.4
CHALLENGES
4.2.4.1
BALANCING AFFORDABILITY, DRIVER EARNINGS, AND PLATFORM MARGINS
4.2.4.2
SCALING SHARED MOBILITY BEYOND HIGH-DENSITY URBAN MARKETS
4.3
UNMET NEEDS AND WHITE SPACES
4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.5
STRATEGIC MOVES BY TIER-1/2/3 SUPPLIERS
4.5.1
OEM VS FLEET MANUFACTURERS STRATEGIES
4.5.2
STRATEGIC MOVES BY KEY COMPANIES
5
INDUSTRY TRENDS
Ride-sharing evolution reshapes mobility, integrating autonomous tech and digital finance for seamless, smart transport.59
5.1
MACROECONOMIC OUTLOOK
5.1.1
GDP TRENDS AND FORECAST
5.1.2
TRENDS IN RIDE SHARING MARKET
5.2
VALUE CHAIN ANALYSIS
5.3
ECOSYSTEM ANALYSIS
5.3.1
RIDE HAILING & MOBILITY PLATFORMS
5.3.2
VEHICLE & FLEET SUPPLIERS
5.3.3
AUTONOMOUS DRIVING & ROBOTAXI TECHNOLOGY
5.3.4
MAPPING, NAVIGATION, & LOCATION INTELLIGENCE
5.3.5
FLEET MANAGEMENT & TELEMATICS
5.3.6
EV CHARGING & ENERGY INFRASTRUCTURE
5.3.7
PAYMENTS & FINANCIAL INFRASTRUCTURE
5.4
PRICING ANALYSIS
5.4.1
AVERAGE COST PER TRIP FOR RIDE SHARING, BY REGION, 2025 (USD)
5.5
KEY CONFERENCES AND EVENTS, 2026–2027
5.6
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
5.7
INVESTMENT AND FUNDING SCENARIO
5.8
CASE STUDY ANALYSIS
5.8.1
UBER LAUNCHES PRIVATE CAR RIDE SHARING TO EXPAND SHARED MOBILITY IN ASSAM
5.8.2
TOYOTA AND DIDI DEVELOP VEHICLE SERVICES SPECIFICALLY FOR RIDE-HAILING DRIVERS
5.8.3
LYFT AND PSTA USE RIDE SHARING TO EXTEND PUBLIC TRANSPORTATION COVERAGE
5.8.4
AGERO USES RIDE SHARING TO SOLVE CUSTOMER TRANSPORTATION GAP AFTER VEHICLE BREAKDOWNS
5.8.5
EZ RIDE USES RIDE SHARING TO SCALE SENIOR TRANSPORTATION WITHOUT EXPANDING ITS OWN FLEET
5.9
DIGITAL FINANCIAL SERVICES AND EMBEDDED ECOSYSTEM
5.9.1
ECOSYSTEM LENDING & BANKING
5.9.2
AI-POWERED WEALTH PLATFORMS
5.9.3
ADVERTISEMENTS & DATA MONETIZATION
5.10
AUTONOMOUS MOBILITY OPERATIONS & INFRASTRUCTURE
5.10.1
AUTONOMOUS SOLUTIONS & DEPOT MANAGEMENT
5.10.2
TRANSIT INTELLIGENCE LICENSING
5.10.3
COMMERCIAL/SPECIALIZED AUTONOMY
5.11
PREMIUM & ENTERPRISE MOBILITY ARCHITECTURE
5.11.1
GLOBAL CHAUFFEUR & EXECUTIVE TRAVEL
5.11.2
CORPORATE, B2B, & WHOLE-NETWORK SOLUTIONS
5.11.3
URBAN INFRASTRUCTURE SOLUTIONS
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations redefine ride-sharing with smart connectivity, telematics, and future-ready mobility solutions.80
6.1
KEY TECHNOLOGIES
6.1.1
VEHICLE-TO-PLATFORM REAL-TIME CONNECTIVITY
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1
SMART PARKING AND CURB MANAGEMENT TECHNOLOGY
6.2.2
VEHICLE TELEMATICS AND REMOTE VEHICLE DIAGNOSTICS
6.3
ADJACENT TECHNOLOGIES
6.3.1
MOBILITY-AS-A-SERVICE INTEGRATION
6.4
TECHNOLOGY/SERVICE ROADMAP
6.4.1
SHORT-TERM ROADMAP
6.4.2
MID-TERM ROADMAP
6.4.3
LONG-TERM ROADMAP
6.5
PATENT ANALYSIS
6.6
FUTURE APPLICATIONS
6.7
IMPACT OF AI/GEN AI ON RIDE SHARING MARKET
6.7.1
TOP USE CASES AND MARKET POTENTIAL
6.7.2
BEST PRACTICES
6.7.3
CASE STUDIES OF AI IMPLEMENTATION
6.7.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.7.5
CLIENTS’ READINESS TO ADOPT AI/GEN AI IN RIDE SHARING MARKET
6.7.6
AI-POWERED WEALTH AND RECURRING REVENUE
6.8
BUSINESS MODEL/ASSET OWNERSHIP
6.8.1
ASSET-LIGHT MARKETPLACE
6.8.2
PLATFORM-OWNED FLEET
6.8.3
DRIVER-OWNED
6.8.4
LEASED/RENTED FLEET
6.8.5
HYBRID MODELS
6.9
TRIP ECONOMICS
6.9.1
SHORT VS LONG TRIPS
6.9.2
PEAK VS OFF-PEAK
6.9.3
OCCUPANCY
6.9.4
TRIPS/VEHICLE/DAY
6.9.5
DEADHEAD MILEAGE
7
REGULATORY LANDSCAPE
Navigate complex micro-mobility regulations with detailed regional insights and licensing requirements.104
7.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.2
KEY LICENSING REQUIREMENTS, BY COUNTRY
7.2.1
CLASSIFICATION OF MICRO-MOBILITY VEHICLES AT REGIONAL LEVEL
7.2.1.1
EUROPE
7.2.1.2
US
7.2.1.3
ASIA
7.2.1.4
LATIN AMERICA
8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Unlock profitability by addressing unmet needs and optimizing cost dynamics in ride-sharing markets.110
8.1
DECISION-MAKING PROCESS
8.2
BUYING CRITERIA
8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES
8.4
UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
8.5
MARKET PROFITABILITY
8.5.1
REVENUE POTENTIAL
8.5.2
COST DYNAMICS
8.5.3
MARGIN OPPORTUNITIES
9
RIDE SHARING MARKET, BY SERVICE TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 14 Data Tables118
9.1
INTRODUCTION
9.2
E-HAILING
9.2.1
EXPANSION OF ON-DEMAND, APP-BASED POINT-TO-POINT MOBILITY TO DRIVE ADOPTION
9.3
CAR SHARING
9.3.1
HIGH COST AND LOW UTILIZATION OF PRIVATE VEHICLE OWNERSHIP TO INCREASE DEMAND
9.4
CAR RENTAL
9.4.1
SHIFT FROM VEHICLE OWNERSHIP TOWARD ASSET-LIGHT MOBILITY TO DRIVE DEMAND FOR CAR RENTAL
9.5
STATION-BASED MOBILITY
9.5.1
INTEGRATION WITH PUBLIC TRANSPORT AND MOBILITY HUBS TO DRIVE STATION-BASED MOBILITY DEMAND
9.6
INDUSTRY INSIGHTS
10
RIDE SHARING MARKET, BY DATA SERVICE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 10 Data Tables127
10.1
INTRODUCTION
10.2
INFORMATION
10.2.1
REAL-TIME TRIP VISIBILITY TO INCREASE RIDER CONFIDENCE AND IMPROVE RIDE EXECUTION
10.3
NAVIGATION
10.3.1
REAL-TIME TRAFFIC AND DYNAMIC ROUTE OPTIMIZATION TO INCREASE NEED FOR NAVIGATION SERVICES
10.4
PAYMENT
10.4.1
PAYMENT DIGITIZATION AND MULTIMODAL INTEGRATION TO INCREASE NEED FOR SEAMLESS PAYMENT SERVICES
10.5
OTHER DATA SERVICES
10.6
INDUSTRY INSIGHTS
11
RIDE SHARING MARKET, BY PROPULSION
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 8 Data Tables135
11.1
INTRODUCTION
11.2
CNG/PETROL
11.2.1
ABILITY TO MEET URBAN AIR QUALITY REQUIREMENTS WHILE RETAINING CONVENTIONAL POWERTRAIN ARCHITECTURE TO SUPPORT ADOPTION
11.3
DIESEL
11.3.1
HIGH TORQUE AND FUEL EFFICIENCY TO SUPPORT INTENSIVE, LONG-DISTANCE RIDE-SHARING OPERATIONS
11.4
ELECTRIC/HYBRID VEHICLE
11.4.1
LOWER RUNNING COST AND SUITABILITY FOR HIGH DAILY UTILIZATION TO MAKE EVS ATTRACTIVE FOR RIDE SHARING FLEETS
11.5
INDUSTRY INSIGHTS
12
RIDE SHARING MARKET, BY BUSINESS MODEL
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 10 Data Tables142
12.1
INTRODUCTION
12.2
B2C
12.2.1
GROWING CONSUMER PREFERENCE FOR APP-BASED, ON-DEMAND POINT-TO-POINT MOBILITY TO DRIVE GROWTH
12.3
B2B/CORPORATE
12.3.1
EMPLOYER DEMAND FOR MANAGED, DATA-ENABLED EMPLOYEE MOBILITY TO DRIVE GROWTH
12.4
P2P
12.4.1
HIGHER UTILIZATION OF PRIVATELY OWNED VEHICLES THROUGH COST SHARING AND DIGITAL MATCHING TO SUPPORT GROWTH
12.5
FLEET-PARTNER/AGGREGATOR
12.5.1
EXPANDING RIDE SUPPLY WITHOUT REQUIRING PLATFORM TO OWN FULL VEHICLE FLEET TO SUPPORT GROWTH
12.6
INDUSTRY INSIGHTS
13
RIDE SHARING MARKET, BY DISTANCE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 6 Data Tables150
13.1
INTRODUCTION
13.2
SHORT DISTANCE
13.2.1
HIGH FREQUENCY OF URBAN TRIPS TO INCREASE DEMAND FOR FLEXIBLE, APP-BASED RIDE SHARING
13.3
LONG DISTANCE
13.3.1
DIRECT POINT-TO-POINT TRAVEL TO MAKE RIDE SHARING ATTRACTIVE FOR AIRPORT, INTERCITY, AND SUBURBAN JOURNEYS
13.4
INDUSTRY INSIGHTS
14
RIDE SHARING MARKET, BY VEHICLE TYPE
Market Size & Growth Rate Forecast Analysis to 2033 in USD Million | 12 Data Tables155
14.1
INTRODUCTION
14.2
HATCHBACK/SEDAN
14.2.1
HIGH UTILIZATION AND LOWER OPERATING COST TO MAKE COMPACT PASSENGER CARS WELL SUITED TO EVERYDAY RIDE SHARING
14.3
SUV/MPV
14.3.1
HIGHER CAPACITY, PASSENGER COMFORT, AND MULTI-PURPOSE UTILITY TO SUPPORT GREATER ADOPTION IN RIDE SHARING
14.4
3-WHEELER
14.4.1
LOW SPACE REQUIREMENT AND AFFORDABLE URBAN CONNECTIVITY TO DRIVE 3-WHEELER ADOPTION IN RIDE SHARING
14.5
2-WHEELER
14.5.1
FASTER, LOWER SPACE, AND LOWER OPERATING COST MOBILITY TO SUPPORT DEMAND FOR SHORT URBAN RIDES
14.6
MICROMOBILITY
14.6.1
SHORT TRIP ECONOMICS, FIRST MILE, AND LAST MILE CONNECTIVITY TO DRIVE ADOPTION OF MICROMOBILITY
14.7
INDUSTRY INSIGHTS
15
RIDE SHARING MARKET, BY REGION
Comprehensive coverage of 7 Regions with country-level deep-dive of 20 Countries | 54 Data Tables.164
15.1
INTRODUCTION
15.2
ASIA PACIFIC
15.2.1
CHINA
15.2.1.1
LARGE URBAN TRAVEL BASE AND MATURE DIGITAL MOBILITY ECOSYSTEM TO DRIVE DEMAND FOR RIDE SHARING SERVICES
15.2.2
INDIA
15.2.2.1
EXPANSION OF PUBLIC TRANSPORT TO INCREASE NEED FOR SHARED FIRST-MILE AND LAST-MILE CONNECTIVITY
15.2.3
JAPAN
15.2.3.1
TRANSPORT SUPPLY SHORTAGES TO ACCELERATE DEMAND FOR FLEXIBLE SHARED MOBILITY IN UNDERSERVED AREAS
15.2.4
SINGAPORE
15.2.4.1
CAR-LITE POLICIES AND INTEGRATED SHARED MOBILITY TO EXPAND ROLE OF RIDE SHARING
15.2.5
INDONESIA
15.2.5.1
FRAGMENTED URBAN MOBILITY AND HIGH MOTORCYCLE DEPENDENCE TO DRIVE DEMAND FOR APP-BASED SHARED TRANSPORT
15.2.6
AUSTRALIA
15.2.6.1
ACCESSIBILITY GAPS TO CREATE DISTINCT DEMAND POOL FOR RIDE SHARING
15.3
EUROPE
15.3.1
UK
15.3.1.1
GROWTH OF SHARED AUTOMATED MOBILITY AND ROBOTAXI SERVICES TO PROPEL MARKET
15.3.2
GERMANY
15.3.2.1
EXPANSION OF APP-BASED ON-DEMAND PUBLIC TRANSPORT TO CREATE STRUCTURED RIDE POOLING DEMAND
15.3.3
FRANCE
15.3.3.1
DEDICATED CARPOOLING LANES AND DIGITAL ENFORCEMENT TO STRENGTHEN RIDE SHARING DEMAND
15.3.4
ITALY
15.3.4.1
EXPANSION OF PROXIMITY-BASED SHARED MOBILITY TO CREATE DEMAND FOR SHORT-DURATION AND LOCAL VEHICLE ACCESS
15.3.5
RUSSIA
15.3.5.1
DIGITAL FORMALIZATION OF TAXI AGGREGATORS TO EXPAND TRUSTED APP-BASED MOBILITY
15.3.6
SPAIN
15.3.6.1
TRANSPORT POVERTY TO INCREASE DEMAND FOR COST SHARING AND SHARED VEHICLE ACCESS
15.3.7
TURKEY
15.3.7.1
RAPID DEPLOYMENT OF CONNECTED ROAD INFRASTRUCTURE TO ENABLE DATA-DRIVEN SHARED MOBILITY
15.3.8
NETHERLANDS
15.3.8.1
GROWTH OF PEER-TO-PEER VEHICLE SHARING TO EXPAND ACCESS TO UNDERUTILIZED PRIVATE VEHICLES
15.4
NORTH AMERICA
15.4.1
US
15.4.1.1
EXPANSION AND ACTIVE MANAGEMENT OF HIGH-OCCUPANCY VEHICLE AND EXPRESS LANES TO CREATE INCENTIVE FOR RIDE SHARING
15.4.2
CANADA
15.4.2.1
RURAL AND REMOTE MOBILITY GAPS TO PUSH DEMAND FOR FLEXIBLE SHARED TRANSPORT
15.4.3
MEXICO
15.4.3.1
EXPANSION OF MOTORCYCLE-BASED PLATFORM MOBILITY TO CREATE RIDE SHARING DEMAND POOL
15.5
REST OF THE WORLD (ROW)
15.5.1
BRAZIL
15.5.1.1
RAPID ADOPTION OF MOTORCYCLE-BASED PASSENGER MOBILITY TO DRIVE DEMAND FOR RIDE SHARING SERVICES
15.5.2
UAE
15.5.2.1
EXPANSION OF CROSS-EMIRATE RIDE-SHARING FOR COST-EFFICIENT INTERCITY TRAVEL TO DRIVE DEMAND
15.5.3
SOUTH AFRICA
15.5.3.1
DIGITAL INTEGRATION OF MINIBUS TAXI NETWORK TO EXPAND APP-BASED SHARED MOBILITY
16
COMPETITIVE LANDSCAPE
Discover strategic shifts and market dominance trends shaping the ride-sharing and micromobility sectors.198
16.1
OVERVIEW
16.2
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2026
16.3
REVENUE ANALYSIS, 2021–2025
16.4
MARKET SHARE ANALYSIS, 2025
16.5
BRAND COMPARISON
16.6
COMPANY EVALUATION MATRIX: RIDE SHARING SERVICE PROVIDERS
16.6.1
STARS
16.6.2
EMERGING LEADERS
16.6.3
PERVASIVE PLAYERS
16.6.4
PARTICIPANTS
16.6.5
COMPANY FOOTPRINT: RIDE SHARING SERVICE PROVIDERS, 2025
16.6.5.1
COMPANY FOOTPRINT
16.6.5.2
REGION FOOTPRINT
16.6.5.3
SERVICE TYPE FOOTPRINT
16.6.5.4
VEHICLE TYPE FOOTPRINT
16.7
COMPANY EVALUATION MATRIX: MICROMOBILITY SERVICE PROVIDERS, 2025
16.7.1
PROGRESSIVE COMPANIES
16.7.2
RESPONSIVE COMPANIES
16.7.3
DYNAMIC COMPANIES
16.7.4
STARTING BLOCKS
16.7.5
COMPANY FOOTPRINT: MICROMOBILITY SERVICE PROVIDERS, 2025
16.7.5.1
COMPANY FOOTPRINT
16.7.5.2
REGION FOOTPRINT
16.7.5.3
SERVICE FOOTPRINT
16.8
COMPANY VALUATION AND FINANCIAL METRICS
16.9
COMPETITIVE SCENARIO
16.9.1
SERVICE LAUNCHES
16.9.2
DEALS
16.9.3
EXPANSIONS
17
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)221
17.1
KEY PLAYERS
17.1.1
DIDI GLOBAL INC.
17.1.1.1
BUSINESS OVERVIEW
17.1.1.2
SERVICES OFFERED
17.1.1.3
RECENT DEVELOPMENTS
17.1.1.3.1
PRODUCT/SERVICE LAUNCHES
17.1.1.3.2
DEALS
17.1.1.3.3
OTHER DEVELOPMENTS
17.1.1.4
MNM VIEW
17.1.1.4.1
KEY STRENGTHS
17.1.1.4.2
STRATEGIC CHOICES
17.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS
17.1.2
UBER TECHNOLOGIES, INC.
17.1.3
LYFT, INC.
17.1.4
BOLT
17.1.5
GRAB
17.1.6
GETT
17.1.7
ANI TECHNOLOGIES PVT. LTD. (OLA)
17.1.8
BLABLACAR
17.1.9
INDRIVE
17.1.10
SIXT
17.1.11
AVIS BUDGET GROUP
17.1.12
HERTZ
17.1.13
ENTERPRISE MOBILITY
17.2
OTHER PLAYERS
17.2.1
WAYMO
17.2.2
CAR2GO
17.2.3
CABIFY
17.2.4
GOGET
17.2.5
VIA TRANSPORTATION, INC.
17.2.6
EASY TAXI
17.2.7
FREE2MOVE
17.2.8
EUROPCAR MOBILITY GROUP
17.2.9
FREENOW
17.2.10
GETAROUND
17.2.11
CAREEM
17.2.12
TURO
18
RESEARCH METHODOLOGY
279
18.1
RESEARCH DATA
18.1.1
SECONDARY DATA
18.1.1.1
LIST OF SECONDARY SOURCES
18.1.1.2
KEY DATA FROM SECONDARY SOURCES
18.1.2
PRIMARY DATA
18.1.2.1
LIST OF PRIMARY PARTICIPANTS
18.1.3
SAMPLING TECHNIQUES AND DATA COLLECTION METHODS
18.2
MARKET SIZE ESTIMATION
18.2.1
BOTTOM-UP APPROACH
18.2.2
TOP-DOWN APPROACH
18.3
DATA TRIANGULATION
18.4
RESEARCH ASSUMPTIONS AND RISK ASSESSMENT
18.5
RESEARCH LIMITATIONS
19
APPENDIX
293
19.1
INSIGHTS FROM INDUSTRY EXPERTS
19.2
DISCUSSION GUIDE
19.3
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
19.4
CUSTOMIZATION OPTIONS
19.4.1
MICRO-MOBILITY MARKET, BY TYPE
19.4.1.1
BICYCLES
19.4.1.2
E-BIKES
19.4.1.3
E-KICK SCOOTERS
19.4.1.4
OTHERS
19.4.2
CAR SHARING MARKET, BY TYPE
19.4.2.1
P2P CAR SHARING
19.4.2.2
CORPORATE CAR SHARING
19.5
RELATED REPORTS
19.6
AUTHOR DETAILS
LIST OF TABLES
TABLE 1
MARKET DEFINITIONS
TABLE 2
CURRENCY EXCHANGE RATES
TABLE 3
OVERVIEW OF MULTIMODAL INTEGRATION EXPANDING RIDE SHARING TAM
TABLE 4
OVERVIEW OF MULTIMODAL INTEGRATION PROVIDED BY KEY PLAYERS
TABLE 5
AVERAGE COST TO OWN AND OPERATE NEW CAR, 2025
TABLE 6
AVERAGE COST OF TOP-SELLING MODELS, 2025
TABLE 7
COMPARISON OF VEHICLE OWNERSHIP VS RIDE SHARING
TABLE 8
OVERVIEW OF REGULATORY DEVELOPMENTS, BY COUNTRIES
TABLE 9
CONVENTIONAL RIDE SHARING VS AV-ENABLED RIDE SHARING
TABLE 10
AV-ENABLED RIDE SHARING, BY KEY COMPANY
TABLE 11
CONNECTED VEHICLE DATA SCALE AND COMMERCIAL OPPORTUNITY
TABLE 12
OVERVIEW PLATFORM ECONOMICS AND DRIVER EARNINGS PRESSURE IN RIDE SHARING
TABLE 13
KEY COST DRIVERS AND THEIR IMPACT ON RIDE SHARING
TABLE 14
STRATEGIC MOVES BY TIER-1/2/3 SUPPLIERS
TABLE 15
OEM VS FLEET MANUFACTURERS STRATEGIES
TABLE 16
STRATEGIC MOVES BY KEY COMPANIES
TABLE 17
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2022–2031
TABLE 18
ROLE OF COMPANIES IN ECOSYSTEM
TABLE 19
AVERAGE COST PER TRIP FOR RIDE SHARING, BY REGION, 2025 (USD)
TABLE 20
RIDE SHARING MARKET: LIST OF KEY CONFERENCES AND EVENTS, 2026–2027
TABLE 21
LIST OF FUNDING, 2025–2026
TABLE 22
OVERVIEW OF LENDING/BANKING ACTIVITIES BY KEY PLAYERS
TABLE 23
OVERVIEW OF AI-POWERED WEALTH MANAGEMENT INITIATIVES BY KEY PLAYERS
TABLE 24
OVERVIEW OF KEY RIDE SHARING COMPANIES MONETIZING ADVERTISING AND MOBILITY DATA
TABLE 25
OVERVIEW OF AUTONOMOUS SOLUTIONS & DEPOT MANAGEMENT INITIATIVES, BY KEY COMPANY
TABLE 26
OVERVIEW OF KEY COMPANIES MONETIZING TRANSIT INTELLIGENCE AND MOBILITY DATA
TABLE 27
COMMERCIAL/SPECIALIZED AUTONOMY: KEY COMPANY DEPLOYMENTS
TABLE 28
OVERVIEW OF CORPORATE, B2B, AND WHOLE NETWORK SOLUTIONS BY MAJOR COMPANIES
TABLE 29
OVERVIEW OF URBAN INFRASTRUCTURE SOLUTIONS, BY KEY COMPANY
TABLE 30
VEHICLE TO PLATFORM REAL-TIME CONNECTIVITY IN RIDE SHARING
TABLE 31
OVERVIEW OF SMART PARKING AND CURB MANAGEMENT TECHNOLOGY
TABLE 32
OPERATIONAL IMPACT OF SMART CURB INTELLIGENCE
TABLE 33
CONVENTIONAL VS CONNECTED VEHICLE DIAGNOSTICS
TABLE 34
MAAS TECHNOLOGY ARCHITECTURE
TABLE 35
PATENT ANALYSIS, 2026
TABLE 36
COMPARISON OF BUSINESS MODEL AND ASSET OWNERSHIP
TABLE 37
TRIP ECONOMICS OF UBER, 2026
TABLE 38
SHORT VS LONG TRIPS
TABLE 39
PEAK VS OFF-PEAK
TABLE 40
LOW OCCUPANCY VS HIGH OCCUPANCY
TABLE 41
LOWER TRIPS/VEHICLE/DAY VS HIGHER TRIPS/VEHICLE/DAY
TABLE 42
NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 43
EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 44
ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
TABLE 45
KEY LICENSING REQUIREMENTS, BY COUNTRY
TABLE 46
EUROPE: LIST OF REGULATORY BODIES, VEHICLE TYPES, AND THEIR FEATURES
TABLE 47
US: LIST OF REGULATORY BODIES, VEHICLE TYPES, AND THEIR FEATURES
TABLE 48
KEY BUYING CRITERIA, BY SERVICE TYPE
TABLE 49
UNMET NEEDS IN RIDE SHARING MARKET, BY END-USE INDUSTRY
TABLE 50
RIDE SHARING MARKET: PROFITABILITY BY SERVICE TYPE
TABLE 51
RIDE SHARING MARKET: PROFITABILITY BY OPERATING MODEL
TABLE 52
RIDE SHARING MARKET: PROFITABILITY BY SERVICE CONFIGURATION
TABLE 53
RIDE SHARING MARKET: REVENUE POTENTIAL BY CORE STREAM
TABLE 54
RIDE SHARING MARKET: REVENUE POTENTIAL BY DIGITAL STREAM
TABLE 55
RIDE SHARING MARKET: COST STRUCTURE AND PROFITABILITY TABLE
TABLE 56
RIDE SHARING MARKET: PLATFORM COST DYNAMICS
TABLE 57
RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 58
RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 59
TOP E-HAILING SERVICE PROVIDERS
TABLE 60
E-HAILING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 61
E-HAILING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 62
TOP CAR SHARING SERVICE PROVIDERS
TABLE 63
CAR SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 64
CAR SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 65
TOP CAR RENTAL SERVICE PROVIDERS
TABLE 66
CAR RENTAL MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 67
CAR RENTAL MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 68
TOP STATION-BASED SERVICE PROVIDERS
TABLE 69
STATION-BASED MOBILITY MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 70
STATION-BASED MOBILITY MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 71
RIDE SHARING MARKET, BY DATA SERVICE, 2022–2025 (USD MILLION)
TABLE 72
RIDE SHARING MARKET, BY DATA SERVICE, 2026–2033 (USD MILLION)
TABLE 73
RIDE SHARING INFORMATION SERVICES MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 74
RIDE SHARING INFORMATION SERVICES MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 75
RIDE SHARING NAVIGATION SERVICES MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 76
RIDE SHARING NAVIGATION SERVICES MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 77
RIDE SHARING PAYMENT SERVICES MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 78
RIDE SHARING PAYMENT SERVICES MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 79
OTHER DATA SERVICES MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 80
OTHER DATA SERVICES MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 81
RIDE SHARING MARKET, BY PROPULSION, 2022–2025 (USD MILLION)
TABLE 82
RIDE SHARING MARKET, BY PROPULSION, 2026–2033 (USD MILLION)
TABLE 83
CNG/PETROL RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 84
CNG/PETROL RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 85
DIESEL RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 86
DIESEL RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 87
ELECTRIC/HYBRID RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 88
ELECTRIC/HYBRID RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 89
RIDE SHARING MARKET, BY BUSINESS MODEL, 2022–2025 (USD MILLION)
TABLE 90
RIDE SHARING MARKET, BY BUSINESS MODEL, 2026–2033 (USD MILLION)
TABLE 91
B2C MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 92
B2C MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 93
B2B/CORPORATE MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 94
B2B/CORPORATE MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 95
P2P MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 96
P2P MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 97
FLEET-PARTNER/AGGREGATOR MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 98
FLEET-PARTNER/AGGREGATOR MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 99
RIDE SHARING MARKET, BY DISTANCE, 2022–2025 (USD MILLION)
TABLE 100
RIDE SHARING MARKET, BY DISTANCE, 2026–2033 (USD MILLION)
TABLE 101
SHORT-DISTANCE RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 102
SHORT-DISTANCE RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 103
LONG-DISTANCE RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 104
LONG-DISTANCE RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 105
RIDE SHARING MARKET, BY VEHICLE TYPE, 2022–2025 (USD MILLION)
TABLE 106
RIDE SHARING MARKET, BY VEHICLE TYPE, 2026–2033 (USD MILLION)
TABLE 107
HATCHBACK/SEDAN RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 108
HATCHBACK/SEDAN RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 109
SUV/MPV RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 110
SUV/MPV RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 111
3-WHEELER RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 112
3-WHEELER RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 113
2-WHEELER RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 114
2-WHEELER RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 115
MICROMOBILITY RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 116
MICROMOBILITY RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 117
RIDE SHARING MARKET, BY REGION, 2022–2025 (USD MILLION)
TABLE 118
RIDE SHARING MARKET, BY REGION, 2026–2033 (USD MILLION)
TABLE 119
ASIA PACIFIC: TOP PLAYERS
TABLE 120
ASIA PACIFIC: RIDE SHARING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 121
ASIA PACIFIC: RIDE SHARING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 122
CHINA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 123
CHINA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 124
INDIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 125
INDIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 126
JAPAN: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 127
JAPAN: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 128
SINGAPORE: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 129
SINGAPORE: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 130
INDONESIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 131
INDONESIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 132
AUSTRALIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 133
AUSTRALIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 134
EUROPE: TOP PLAYERS
TABLE 135
EUROPE: RIDE SHARING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 136
EUROPE: RIDE SHARING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 137
UK: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 138
UK: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 139
GERMANY: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 140
GERMANY: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 141
FRANCE: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 142
FRANCE: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 143
ITALY: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 144
ITALY: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 145
RUSSIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 146
RUSSIA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 147
SPAIN: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 148
SPAIN: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 149
TURKEY: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 150
TURKEY: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 151
NETHERLANDS: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 152
NETHERLANDS: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 153
NORTH AMERICA: TOP PLAYERS
TABLE 154
NORTH AMERICA: RIDE SHARING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 155
NORTH AMERICA: RIDE SHARING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 156
US: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 157
US: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 158
CANADA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 159
CANADA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 160
MEXICO: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 161
MEXICO: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 162
ROW: TOP PLAYERS
TABLE 163
ROW: RIDE SHARING MARKET, BY COUNTRY, 2022–2025 (USD MILLION)
TABLE 164
ROW: RIDE SHARING MARKET, BY COUNTRY, 2026–2033 (USD MILLION)
TABLE 165
BRAZIL: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 166
BRAZIL: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 167
UAE: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 168
UAE: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 169
SOUTH AFRICA: RIDE SHARING MARKET, BY SERVICE TYPE, 2022–2025 (USD MILLION)
TABLE 170
SOUTH AFRICA: RIDE SHARING MARKET, BY SERVICE TYPE, 2026–2033 (USD MILLION)
TABLE 171
RIDE SHARING MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, 2026
TABLE 172
RIDE SHARING MARKET: DEGREE OF COMPETITION
TABLE 173
RIDE SHARING SERVICE PROVIDERS: REGION FOOTPRINT
TABLE 174
RIDE SHARING SERVICE PROVIDERS: SERVICE TYPE FOOTPRINT
TABLE 175
RIDE SHARING SERVICE PROVIDERS: VEHICLE TYPE FOOTPRINT
TABLE 176
MICROMOBILITY SERVICE PROVIDERS: REGION FOOTPRINT
TABLE 177
MICROMOBILITY SERVICE PROVIDERS: SERVICE FOOTPRINT
TABLE 178
RIDE SHARING MARKET: SERVICE LAUNCHES, JANUARY 2023–AUGUST 2026
TABLE 179
RIDE SHARING MARKET: DEALS, JANUARY 2023–AUGUST 2026
TABLE 180
RIDE SHARING MARKET: EXPANSIONS, JANUARY 2023–AUGUST 2026
TABLE 181
DIDI GLOBAL INC.: COMPANY OVERVIEW
TABLE 182
DIDI GLOBAL INC.: SERVICES OFFERED
TABLE 183
DIDI GLOBAL INC.: PRODUCT/SERVICE LAUNCHES
TABLE 184
DIDI GLOBAL INC.: DEALS
TABLE 185
DIDI GLOBAL INC.: OTHER DEVELOPMENTS
TABLE 186
UBER TECHNOLOGIES, INC.: COMPANY OVERVIEW
TABLE 187
UBER TECHNOLOGIES, INC.: SERVICES OFFERED
TABLE 188
UBER TECHNOLOGIES, INC.: SERVICE LAUNCHES
TABLE 189
UBER TECHNOLOGIES, INC.: DEALS
TABLE 190
UBER TECHNOLOGIES, INC.: EXPANSIONS
TABLE 191
LYFT, INC.: COMPANY OVERVIEW
TABLE 192
LYFT, INC.: SERVICES OFFERED
TABLE 193
LYFT, INC.: SERVICE LAUNCHES
TABLE 194
LYFT, INC.: DEALS
TABLE 195
LYFT, INC.: EXPANSIONS
TABLE 196
BOLT: COMPANY OVERVIEW
TABLE 197
BOLT: SERVICES OFFERED
TABLE 198
BOLT: SERVICE LAUNCHES
TABLE 199
BOLT: DEALS
TABLE 200
BOLT: EXPANSIONS
TABLE 201
GRAB: COMPANY OVERVIEW
TABLE 202
GRAB: SERVICES OFFERED
TABLE 203
GRAB: SERVICE LAUNCHES/DEVELOPMENTS
TABLE 204
GRAB: DEALS
TABLE 205
GETT: COMPANY OVERVIEW
TABLE 206
GETT: SERVICES OFFERED
TABLE 207
GETT: SERVICE LAUNCHES
TABLE 208
GETT: DEALS
TABLE 209
ANI TECHNOLOGIES PVT. LTD (OLA): COMPANY OVERVIEW
TABLE 210
ANI TECHNOLOGIES PVT. LTD. (OLA): SERVICES OFFERED
TABLE 211
BLABLACAR: COMPANY OVERVIEW
TABLE 212
BLABLACAR: SERVICES OFFERED
TABLE 213
BLABLACAR: SERVICE LAUNCHES
TABLE 214
BLABLACAR: DEALS
TABLE 215
BLABLACAR: EXPANSIONS
TABLE 216
INDRIVE: COMPANY OVERVIEW
TABLE 217
INDRIVE: SERVICES OFFERED
TABLE 218
INDRIVE: DEALS
TABLE 219
INDRIVE: EXPANSIONS
TABLE 220
SIXT: COMPANY OVERVIEW
TABLE 221
SIXT: SERVICES OFFERED
TABLE 222
SIXT: SERVICE LAUNCHES
TABLE 223
SIXT: DEALS
TABLE 224
AVIS BUDGET GROUP: COMPANY OVERVIEW
TABLE 225
AVIS BUDGET GROUP: SERVICES OFFERED
TABLE 226
HERTZ: COMPANY OVERVIEW
TABLE 227
HERTZ: SERVICES OFFERED
TABLE 228
ENTERPRISE MOBILITY: COMPANY OVERVIEW
TABLE 229
ENTERPRISE MOBILITY: SERVICES OFFERED
TABLE 230
WAYMO: COMPANY OVERVIEW
TABLE 231
CAR2GO: COMPANY OVERVIEW
TABLE 232
CABIFY: COMPANY OVERVIEW
TABLE 233
GOGET: COMPANY OVERVIEW
TABLE 234
VIA TRANSPORTATION, INC.: COMPANY OVERVIEW
TABLE 235
EASY TAXI: COMPANY OVERVIEW
TABLE 236
FREE2MOVE: COMPANY OVERVIEW
TABLE 237
EUROPCAR MOBILITY GROUP: COMPANY OVERVIEW
TABLE 238
FREENOW: COMPANY OVERVIEW
TABLE 239
GETAROUND: COMPANY OVERVIEW
TABLE 240
CAREEM: COMPANY OVERVIEW
TABLE 241
TURO: COMPANY OVERVIEW
LIST OF FIGURES
FIGURE 1
MARKET SCENARIO
FIGURE 2
GLOBAL RIDE SHARING MARKET, 2022–2033
FIGURE 3
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN RIDE SHARING MARKET, 2023–2026
FIGURE 4
DISRUPTIONS INFLUENCING GROWTH OF RIDE SHARING MARKET
FIGURE 5
HIGH-GROWTH SEGMENTS IN RIDE SHARING MARKET
FIGURE 6
ASIA PACIFIC TO EXPERIENCE RAPID GROWTH DURING FORECAST PERIOD
FIGURE 7
RISING URBAN MOBILITY DEMAND TO PROPEL MARKET
FIGURE 8
HIGH TRIP FREQUENCY, APP-BASED ON-DEMAND MATCHING, BROAD GEOGRAPHIC COVERAGE, AND LOW ASSET OWNERSHIP REQUIREMENTS MAKE E-HAILING THE MOST SCALABLE SHARED-MOBILITY MODEL
FIGURE 9
LOWER OPERATING COSTS, ZERO TAILPIPE EMISSIONS, ACCESS TO CHARGING INFRASTRUCTURE, REGULATORY SUPPORT, AND GROWING CONSUMER PREFERENCE FOR CLEANER MOBILITY MAKE EVS THE FASTEST GROWING SEGMENT
FIGURE 10
HIGH CUSTOMER REACH, DIRECT APP BASED BOOKINGS, FREQUENT INDIVIDUAL TRIPS, SIMPLE DIGITAL PAYMENTS, AND ESTABLISHED PLATFORM NETWORKS MAKE B2C THE LARGEST SEGMENT IN BUSINESS MODEL
FIGURE 11
REAL TIME ROUTE GUIDANCE, TRAFFIC BASED TRIP OPTIMIZATION, PICKUP AND DROP OFF ACCURACY, AND INTEGRATION WITH RIDE MATCHING MAKE NAVIGATION A CORE SEGMENT IN DATA SERVICE
FIGURE 12
HIGH PASSENGER CAPACITY, LOWER PURCHASE AND OPERATING COSTS, BETTER FUEL EFFICIENCY, EASY AVAILABILITY, AND SUITABILITY FOR FREQUENT URBAN TRIPS MAKE HATCHBACKS/SEDANS THE PREFERRED VEHICLE TYPE ACROSS RIDESHARING SERVICES
FIGURE 13
HIGH URBAN TRIP FREQUENCY, DAILY COMMUTING DEMAND, LOWER FARES, SHORTER TRAVEL TIMES, AND STRONG FIRST MILE AND LAST MILE USE MAKE SHORT DISTANCE TRIPS MORE COMMON ACROSS RIDESHARING SERVICES
FIGURE 14
ASIA PACIFIC TO ACCOUNT FOR LARGEST SHARE OF RIDE SHARING MARKET IN 2026
FIGURE 15
RIDE SHARING MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES
FIGURE 16
VALUE CHAIN ANALYSIS
FIGURE 17
ECOSYSTEM ANALYSIS
FIGURE 18
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
FIGURE 19
NUMBER OF DEALS, 2022–2025
FIGURE 20
PATENTS APPLIED AND GRANTED, 2016–2026
FIGURE 21
FUTURE APPLICATIONS
FIGURE 22
KEY BUYING CRITERIA, BY SERVICE TYPE
FIGURE 23
RIDE SHARING MARKET, BY SERVICE TYPE, 2026 VS 2033 (USD MILLION)
FIGURE 24
RIDE SHARING MARKET, BY DATA SERVICE, 2026 VS. 2033 (USD MILLION)
FIGURE 25
RIDE SHARING MARKET, BY PROPULSION, 2026 VS. 2033 (USD MILLION)
FIGURE 26
ANNUAL FUEL COSTS, GASOLINE VS. CNG VS. ELECTRICITY, 2025
FIGURE 27
ANNUAL COST SAVINGS, EV VS. ICE, 2025
FIGURE 28
RIDE SHARING MARKET, BY BUSINESS MODEL, 2026 VS 2033 (USD MILLION)
FIGURE 29
RIDE SHARING MARKET, BY DISTANCE, 2026 VS. 2033 (USD MILLION)
FIGURE 30
RIDE SHARING MARKET, BY VEHICLE TYPE, 2026 VS. 2033 (USD MILLION)
FIGURE 31
RIDE SHARING MARKET, BY REGION, 2026 VS. 2033 (USD MILLION)
FIGURE 32
ASIA PACIFIC: RIDE SHARING MARKET SNAPSHOT
FIGURE 33
EUROPE: RIDE SHARING MARKET SNAPSHOT
FIGURE 34
NORTH AMERICA: RIDE SHARING MARKET SNAPSHOT
FIGURE 35
ROW: RIDE SHARING MARKET SNAPSHOT
FIGURE 36
REVENUE ANALYSIS, 2021–2025
FIGURE 37
MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025
FIGURE 38
BRAND COMPARISON
FIGURE 39
RIDE SHARING MARKET: COMPANY EVALUATION MATRIX (RIDE SHARING SERVICE PROVIDERS), 2025
FIGURE 40
RIDE SHARING SERVICE PROVIDERS: COMPANY FOOTPRINT
FIGURE 41
RIDE SHARING MARKET: COMPANY EVALUATION MATRIX (MICROMOBILITY SERVICE PROVIDERS), 2025
FIGURE 42
MICROMOBILITY SERVICE PROVIDERS: COMPANY FOOTPRINT
FIGURE 43
COMPANY VALUATION
FIGURE 44
FINANCIAL METRICS (EV/EBITDA)
FIGURE 45
DIDI GLOBAL INC.: COMPANY SNAPSHOT
FIGURE 46
UBER TECHNOLOGIES, INC.: COMPANY SNAPSHOT
FIGURE 47
LYFT, INC.: COMPANY SNAPSHOT
FIGURE 48
GRAB: COMPANY SNAPSHOT
FIGURE 49
SIXT: COMPANY SNAPSHOT
FIGURE 50
AVIS BUDGET GROUP: COMPANY SNAPSHOT
FIGURE 51
HERTZ: COMPANY SNAPSHOT
FIGURE 52
RESEARCH DESIGN
FIGURE 53
RESEARCH DESIGN MODEL
FIGURE 54
BREAKDOWN OF PRIMARY INTERVIEWS
FIGURE 55
RESEARCH METHODOLOGY: HYPOTHESIS BUILDING
FIGURE 56
BOTTOM-UP APPROACH
FIGURE 57
TOP-DOWN APPROACH (PROPULSION)
FIGURE 58
TOP-DOWN APPROACH (DATA SERVICE)
FIGURE 59
FACTOR ANALYSIS FOR MARKET SIZING: DEMAND AND SUPPLY SIDES
FIGURE 60
DATA TRIANGULATION
The research study involved extensive use of secondary sources, such as company annual reports/presentations, industry association publications, automotive magazine articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the ride sharing market. Primary interviews were conducted to obtain and verify critical qualitative and quantitative information and assess the industry's prospects. Primary sources include experts from core and related industries, suppliers, manufacturers, distributors, service providers, technology developers, and organizations related to various segments of the ride sharing market value chain. Detailed interviews were conducted with various primary respondents, including key industry participants, Subject Matter Experts (SMEs), C-level executives of key market players, and industry consultants.
Secondary ResearchSecondary sources referred to for this research study include automotive industry organizations such as the International Council on Clean Transportation (ICCT), US National Highway Traffic Safety Administration (NHTSA), China Center for Urban Development (CCUD), International Association of Public Transport (UITP), International Transport Forum (ITF), National Association of City Transportation Officials (NACTO), among others; corporate filings such as annual reports, investor presentations, and financial statements; and trade, business, and automotive associations. Secondary data was collected and analyzed to determine the overall market size, which was further validated through primary research.
Primary ResearchExtensive primary research was conducted after acquiring an understanding of the ride sharing market scenario through secondary research. Several primary interviews were conducted with market experts from the mobility service providers and technology providers across three major regions, namely, Asia Pacific, Europe, and North America. Approximately 65% and 35% of the primary interviews were conducted with the mobility service providers and the technology providers, respectively. Primary data were collected through questionnaires, emails, and telephonic interviews. Various departments within organizations, including sales, operations, and administration, were contacted to provide a holistic viewpoint in reports while canvassing primary data. After interacting with industry participants, some brief sessions were conducted with experienced independent consultants to reinforce the findings from the primary data. This, along with the opinions of in-house subject matter experts, led to the findings delineated in the rest of this report.
Primary interviews were conducted to gather insights, including ride sharing market sizing estimation and forecast, future trends, and upcoming technologies in the market. Data triangulation of all these points was done using the information gathered from secondary research and model mapping. Stakeholders from the demand and supply sides were interviewed to understand their views on the aforementioned points.

Note: Others include sales, marketing, and product managers.
Company tiers are based on the value chain; revenue of the company is not considered.
To know about the assumptions considered for the study, download the pdf brochure
A detailed market estimation approach was followed to estimate and validate the value and volume of the ride sharing market and other dependent submarkets, as mentioned below:

All percentage shares, splits, and breakdowns were determined using secondary sources and verified by primary sources. All parameters that are said to affect the markets covered in this research study were accounted for, viewed in extensive detail, and analyzed to obtain the final quantitative and qualitative data.
|
Type |
Definition |
|
Ride sharing |
Ride sharing (also called mobility on demand) is the availability of mobility options such as cars or two-wheelers for a point-to-point commute. Ride sharing services are a substitute for personal vehicles and traditional transport networks. These services have evolved primarily in the last decade with the advent of the Internet and the growing usage of smartphones. The modern ride sharing service industry has revolutionized the mobility-as-a-service landscape. |
|
E-hailing |
It is sharing and picking up a ride-sharing service through mobile- or web-based services. The passenger is driven to the destination for an agreed monetary payment. For instance, the user would hail a ride through a particular app or website and pay distance- and time-based fees. Popular ride-sharing examples are taxi aggregators such as Uber, Lyft, and Didi Chuxing. |
|
Car Sharing & Rental |
Car sharing and car rental are also a part of the ride sharing service. Car sharing is the shared use of mobility, which involves sharing a car by multiple people for various predetermined destinations, whereas car rental is renting a car by an individual or a group of people for a common destination. |
|
Station-based mobility |
Station-based mobility provides stacks and racks of vehicles at closely spaced intervals throughout a city. Station-based mobility is convenient and low-cost. Users get the benefits of an automobile without the associated high costs and parking requirements. |
|
Micro-mobility vehicles |
Micro-mobility vehicles are used for short distances. The vehicles used are like bicycles (electric and peddled), scooters (pop scooters and mopeds), and others (powered two-wheelers, two-seater small cars). |
|
Short-distance ride |
A short-distance ride is assumed to be the distance covered within the vicinity of the city, i.e., 30–40 km (18.6–24.8 miles). |
|
Long-distance ride |
A long-distance ride is assumed to be the distance covered outside the vicinity of the city, i.e., more than 40 km (24.8 miles). |
MarketsandMarkets offers the following customizations for this market report:
Note: The micro-mobility market can be offered by type at the country level.
Note: The car sharing market can be offered by type at the country level.


PRODUCT DIRECTOR, WEASLER
Global Provider of Industrial Actuation & Control Solutions
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Vice President
A global technology company that develops safer, greener and more connected solutions.
We contracted with MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our interest in the Fleet Management space. The team successfully completed the work on time and at the pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with us to help us get the visibility we needed to make an investment.
We have subsequently used MarketsandMarkets again related to Smart Cities to good results.