Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASA
USD 35.27
MARKET SIZE, 2033

CAGR 5.8%
(2026-2033)

350
REPORT PAGES

150
MARKET TABLES
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
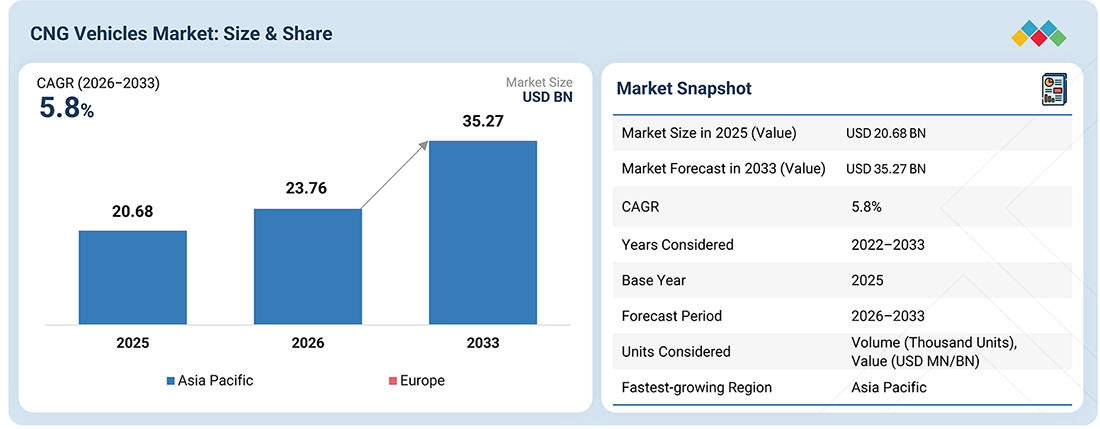
The CNG vehicles market size is projected to grow from USD 23.76 billion in 2026 to USD 35.27 billion by 2033, at a CAGR of 5.8%. The CNG vehicles market is moving toward higher-pressure fuel systems and better integration of fuel storage, injection, pressure regulation, and engine control systems. The strategic focus is shifting toward platform-level CNG integration, where OEMs such as Maruti Suzuki, Tata Motors, IVECO, and Hyundai are optimizing tank packaging, gas injection, combustion calibration, and electronic controls to extend CNG and LNG applications across passenger and high-utilization commercial vehicles. Connected fuel management and biomethane compatibility are also enabling OEMs and fleet operators to optimize operating costs and extend CNG platforms beyond conventional natural gas applications.
MARKET SNAPSHOT:
Market Size (2025): USD 20.68 Billion
Current Market Size (2026): USD 23.76 Billion
Projected Market Size (2033): USD 35.27 Billion
CAGR (2026–2033): 5.8%
BY REGION
By region, Asia Pacific is expected to be the largest market during the forecast period.
BY ENGINE TYPE
By engine type, the bi-Fuel segment is expected to dominate the CNG vehicles market, with an 83.0% share in 2026.
BY FITTING TYPE
By fitting type, OEMs are projected to experience the highest growth rate during the forecast period.
BY FUEL TYPE
By fuel type, CNG is the fastest-growing segment in the CNG vehicles market, with a CAGR of 7.7% from 2026 to 2033.
BY TANK TYPE
By tank type, the Type 2 segment is expected to be the fastest-growing in the CNG vehicles market, with a CAGR of 17.4% from 2026 to 2033.
BY VEHICLE TYPE
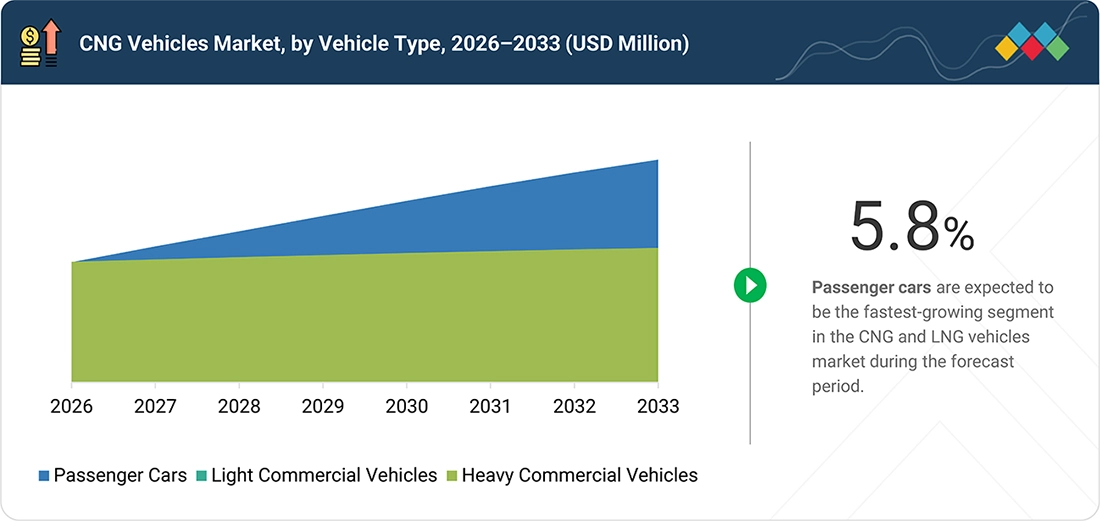
By vehicle type, passenger cars are the fastest-growing segment in the CNG vehicles market, with a CAGR of 9.2% from 2026 to 2033.
COMPETITIVE LANDSCAPE - KEY PLAYERS
Leading CNG vehicle OEMs, including MARUTI SUZUKI INDIA LIMITED (India), Tata Motors Limited (India), and Hyundai Motor Company (South Korea), are expanding their CNG vehicle portfolios across passenger and light commercial vehicle segments, with a focus on factory-fitted CNG powertrains, fuel efficiency, and application-specific vehicle platforms.
COMPETITIVE LANDSCAPE - STARTUPS/SMES
AB Volvo (Sweden) and Sinotruk (China) have distinguished themselves among startups and SMEs by establishing strong footholds in specialized niches, underscoring their potential as emerging market leaders.
The CNG vehicles market is being shaped by the need to optimize the entire gas-handling system rather than individual components. OEMs and Tier 1 suppliers are focusing on coordinated calibration of gas injectors, pressure regulators, engine control units, and oxygen sensing to maintain stable air-fuel ratios across varying tank pressure and operating conditions. In commercial vehicles, this is driving development of higher capacity fuel storage and pressure management systems that can support longer duty cycles without excessive packaging penalties. At the same time, engineers are optimizing cylinder material selection, valve architecture, and mounting design to reduce system mass while meeting pressure and crash safety requirements.
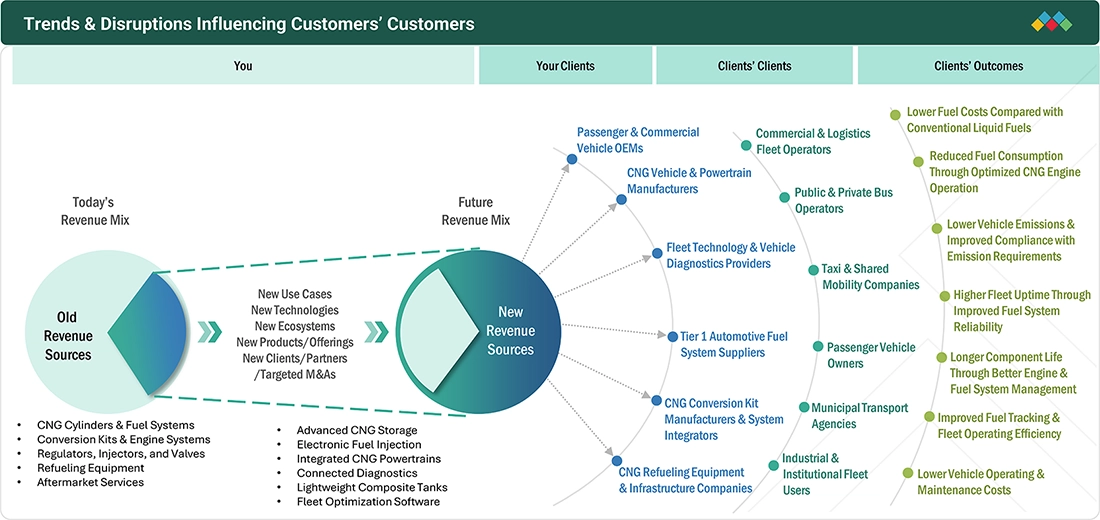
The CNG vehicles landscape is shifting from conventional natural-gas applications toward advanced, integrated, lower-emission powertrain solutions, supported by the growing use of biomethane and Bio-LNG. Future opportunities are linked to lightweight and high-capacity gas storage systems, advanced fuel injection, improved engine technologies, and expanding CNG/LNG fueling infrastructure. These developments enable OEMs and fleet operators to meet the operating requirements of high-utilization commercial vehicles, public transport fleets, and long-haul trucks. End users benefit from lower fuel costs, longer driving range, improved fuel efficiency, reduced emissions, and lower operating costs.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Drivers
Impact
Level


RESTRAINTS
Impact
Level


OPPORTUNITIES
Impact
Level


CHALLENGES
Impact
Level

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
CNG is becoming more attractive for passenger cars and LCVs where lower fuel costs can reduce daily operating expenses, particularly for high-mileage users and commercial fleets. LNG is gaining relevance in heavy trucks because its higher energy density supports longer driving ranges and reduces the need for frequent refueling. OEMs are improving CNG and LNG powertrains through optimized engine calibration, higher torque output, improved fuel efficiency, and larger onboard fuel storage. These improvements support wider use of CNG passenger cars and LCVs and LNG heavy trucks in high-mileage applications.
CNG passenger cars and LCVs depend on convenient station coverage for daily and intercity operations, while LNG heavy trucks require strategically located stations along major freight corridors. Uneven distribution of CNG and LNG infrastructure can increase route-planning requirements, limit vehicle utilization, and discourage fleet expansion in areas with insufficient fueling access. The availability and geographic coverage of refueling stations therefore remain important factors influencing CNG adoption in passenger cars and LCVs and LNG adoption in heavy trucks.
Biomethane can be used in existing CNG passenger cars and LCVs with compatible powertrains and fueling infrastructure, while Bio-LNG provides a renewable fuel pathway for LNG-powered heavy trucks. Increasing renewable gas production and distribution can help fleet operators reduce lifecycle emissions without requiring a fundamental change in vehicle architecture, supporting continued adoption of CNG and LNG vehicles.
Differences in emission requirements, vehicle homologation, cylinder and LNG tank certification, fuel-quality specifications, and refueling standards across countries increase engineering and compliance requirements for CNG and LNG vehicle platforms. OEMs and suppliers may therefore need to adapt engine calibration, fuel-system components, storage configurations, and certification processes for individual markets, increasing development complexity and investment requirements when scaling gas-powered vehicles across regions.
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
|
|
Offers factory-fitted CNG passenger cars and LCVs for urban commuting, small-business mobility, and commercial fleet applications. | Reduces fuel expenditure, lowers operating costs, and provides an alternative to gasoline-powered mobility. |
|
|
Deploys CNG-powered passenger and light commercial vehicles for urban transportation, last-mile delivery, and small commercial fleets. | Reduces fuel costs, supports lower-emission urban transport, and improves fleet operating economics. |
|
|
Uses CNG powertrains in commercial and fleet-oriented vehicle applications, particularly where operating economics and lower emissions are priorities. | Provides fuel-cost savings and supports transition from conventional gasoline/diesel vehicles. |
|
|
Manufactures CNG buses and trucks for urban public transportation, staff transportation, and commercial freight applications. | Reduces fuel costs and tailpipe emissions while supporting high-utilization fleet operations. |
|
|
Provides CNG-powered buses and trucks for urban distribution, passenger transportation, and regional logistics. | Lowers operating expenditure and provides an alternative to diesel for suitable routes. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
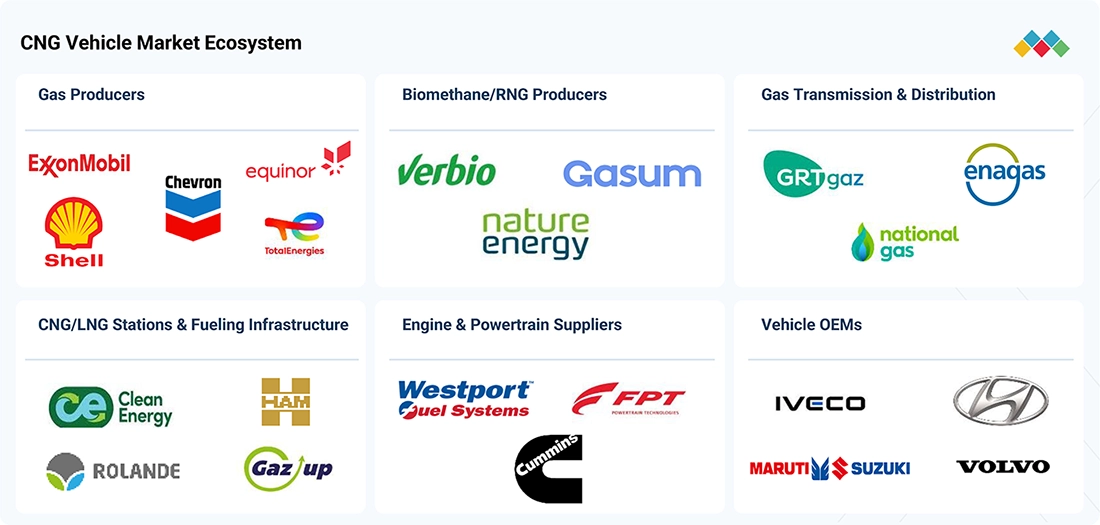
The CNG vehicles market ecosystem is shifting from a fuel supply chain to an integrated gas mobility ecosystem. Natural gas producers and suppliers provide CNG and LNG feedstock, while biomethane producers add renewable gas that can run compatible natural gas vehicle platforms. Gas transmission and distribution companies connect production and import sources with fueling infrastructure, while station operators develop compression, storage, dispensing, and fleet refueling systems. Engine and powertrain suppliers provide natural gas engines, fuel injection, gas delivery, and electronic control technologies, which vehicle OEMs integrate into trucks, buses, and other platforms. Coordination between fuel suppliers, infrastructure operators, powertrain companies, and OEMs is improving fuel availability, vehicle compatibility, and system integration across different operating applications. This ecosystem is also creating opportunities for suppliers to participate beyond individual components through integrated fuel, powertrain, and fleet solutions.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Sequential injection systems are expected to capture the largest market share as OEMs increasingly adopt electronically controlled gas injection to achieve more precise fuel metering and maintain stable air-fuel ratios across varying engine loads.
OEM-fitted CNG systems are expected to witness the fastest growth as automakers increasingly integrate fuel tanks, injectors, pressure regulators, engine control units, and safety systems during vehicle development.
Bi-fuel vehicles are expected to capture the largest market share as passenger and commercial vehicle OEMs continue to blend CNG with gasoline to provide operating flexibility while keeping CNG as the primary fuel for regular operation.
CNG is expected to lead the CNG vehicles market, supported by broader adoption of factory-fitted CNG passenger cars and LCVs, particularly in price-sensitive, high-mileage applications. Lower fuel costs and the ability to use existing CNG refueling networks also support faster adoption.
Type 4 cylinders are expected to see the fastest growth, as their polymer liner and composite construction reduce cylinder weight, allowing OEMs to increase vehicle payload and optimize CNG tank packaging.
Passenger cars are expected to see the fastest growth as OEMs expand factory-fitted CNG portfolios with compact tank configurations and integrated fuel systems that preserve cabin and luggage space.
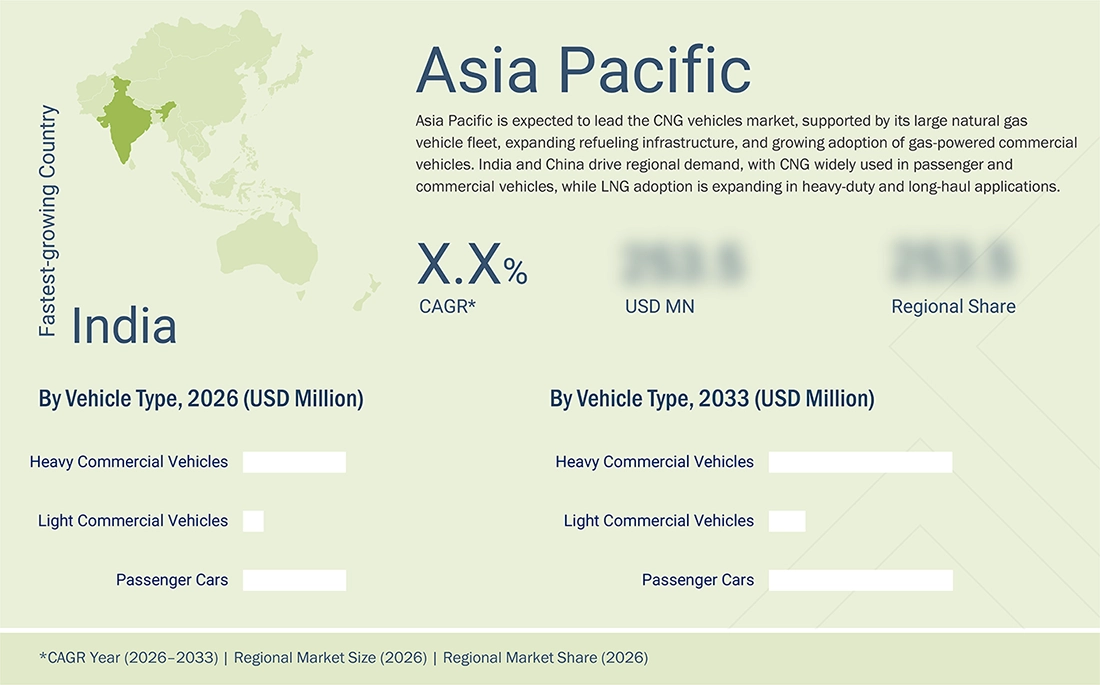
Asia Pacific is expected to lead the CNG vehicles market because it combines strong demand for factory-fitted CNG passenger cars with rapid expansion of LNG heavy-truck infrastructure. India continues to expand CNG adoption through new OEM model launches, increasing CNG station coverage, and Bio-CNG production, supporting passenger cars and light commercial vehicles. China is strengthening LNG adoption by expanding highway refueling corridors and promoting LNG trucks for long-distance freight transport. The region also benefits from supportive government policies, growing renewable gas integration, and a large commercial vehicle base, creating sustained demand for CNG and LNG vehicles across both urban and freight applications.
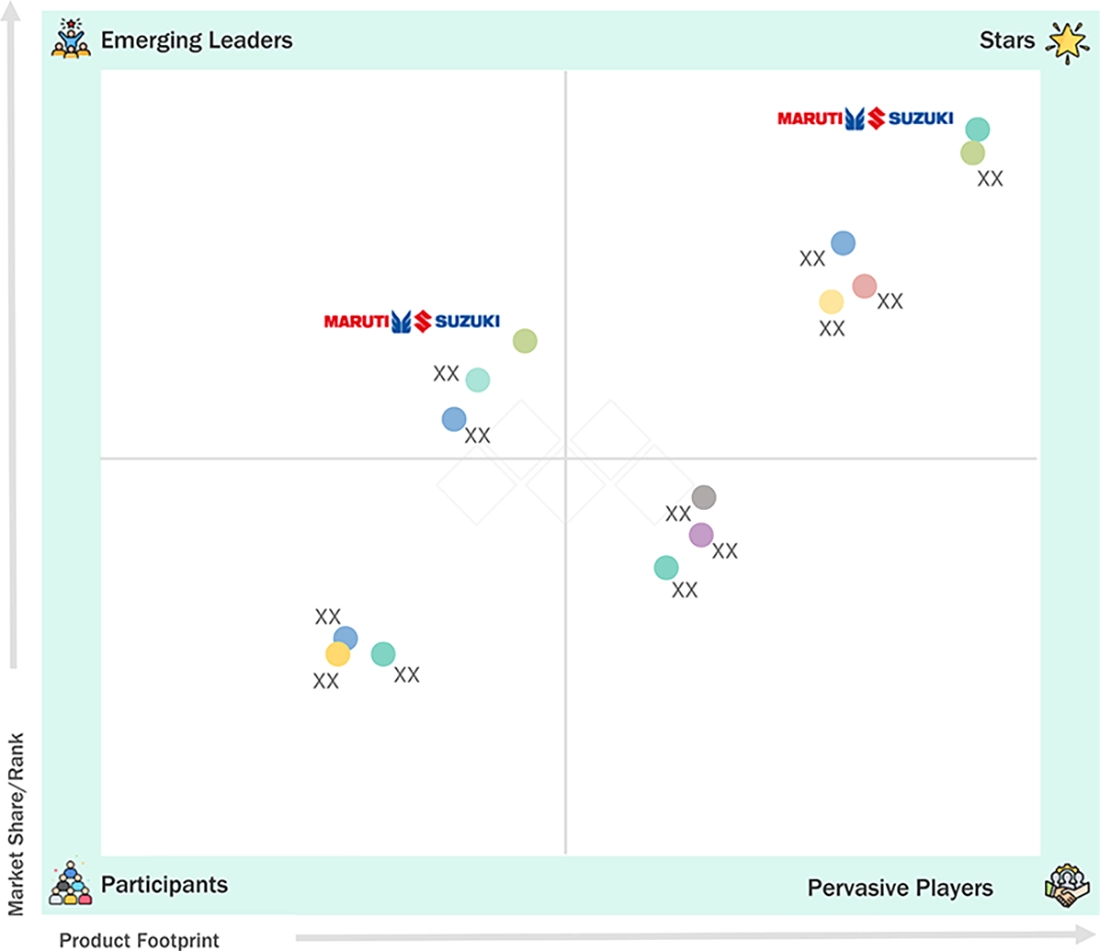
In the CNG vehicles market matrix, Maruti Suzuki India Limited (Star) leads with a strong presence in the CNG passenger-car segment, supported by a broad factory-fitted S-CNG portfolio covering hatchbacks, sedans, SUVs, and MPVs, along with its established sales and service network. Eicher (Emerging Leader) is strengthening its position through LNG heavy-truck platforms such as the Pro 6055 LNG and Pro 8055 LNG, supported by long-haul applications, connected fleet solutions, and partnerships to develop LNG fueling corridors.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 20.68 Billion |
| Market Forecast in 2026 (Value) | USD 23.76 Billion |
| Market Forecast in 2033 (Value) | USD 35.27 Billion |
| Growth Rate | CAGR of 5.8% from 2026–2033 |
| Years Considered | 2022–2033 |
| Base Year | 2025 |
| Forecast Period | 2026–2033 |
| Units Considered | Volume (Thousand Units), Value (USD Million/Billion) |
| Report Coverage | Revenue Forecast, Company Share, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | Asia Pacific, Europe, North America, Rest of the World |
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Global Natural Gas Vehicle OEM (Europe) |
|
|
| CNG Vehicle OEM (India) |
|
|
| LNG Truck Manufacturer (China) |
|
|
| Gas Infrastructure Provider (Europe) |
|
|
| Automotive Component Supplier (Asia Pacific) |
|
|
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
15
2
EXECUTIVE SUMMARY
3
PREMIUM INSIGHTS
4
MARKET OVERVIEW
Highlights the market structure, growth drivers, restraints, and near-term inflection points influencing performance.4.1
INTRODUCTION
4.2
MARKET DYNAMICS
4.2.1
DRIVERS
4.2.1.1
FLEET TCO ADVANTAGE ACCELERATING DIESEL-TO-GAS SUBSTITUTION
4.2.1.2
DIESEL-COMPARABLE POWERTRAINS EXPANDING NATURAL-GAS VIABILITY INTO HEAVY-DUTY & LONG-HAUL APPLICATIONS
4.2.2
RESTRAINTS
4.2.2.1
UNEVEN REFUELING INFRASTRUCTURE CONSTRAINING CROSS-REGIONAL GAS VEHICLE DEPLOYMENT
4.2.3
OPPORTUNITIES
4.2.3.1
BIOMETHANE INTEGRATION EXTENDING THE COMMERCIAL VIABILITY OF GAS POWERTRAINS
4.2.3.2
DEVELOPMENT OF DEDICATED GAS-FUELING CORRIDORS FOR COMMERCIAL MOBILITY
4.2.3.3
WASTE-TO-BIOMETHANE INTEGRATION CREATING CLOSED-LOOP MUNICIPAL FLEET ECOSYSTEMS
4.2.4
CHALLENGES
4.2.4.1
REGULATORY DIVERGENCE INCREASING INVESTMENT RISK ACROSS GAS MOBILITY MARKETS
4.3
UNMET NEEDS & WHITE SPACES
4.4
INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5
INDUSTRY TRENDS
Captures industry movement, adoption patterns, and strategic signals across key end-use segments and regions.5.1
MACROECONOMIC INDICATORS
5.1.1
INTRODUCTION
5.1.2
GDP TRENDS & FORECAST
5.1.3
TRENDS IN GLOBAL ALTERNATIVE FUEL VEHICLES MARKET
5.1.4
TRENDS IN GLOBAL AUTOMOTIVE INDUSTRY
5.2
ECOSYSTEM ANALYSIS
5.3
SUPPLY CHAIN ANALYSIS
5.4
PRICING ANALYSIS
5.4.1
AVERAGE SELLING PRICE TREND OF CNG PASSENGER CARS, BY KEY PLAYER, 2023–2025
5.4.2
AVERAGE SELLING PRICE TREND OF CNG PASSENGER CARS, BY REGION, 2023–2025
5.5
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES
5.6
INVESTMENT & FUNDING SCENARIO
5.7
TRADE ANALYSIS
5.7.1
IMPORT SCENARIO (HS CODE 8703)
5.7.2
EXPORT SCENARIO (HS CODE 8703)
5.8
KEY CONFERENCES & EVENTS, 2026–2027
5.9
CASE STUDY ANALYSIS
5.10
OEM & FLEET STRATEGY ANALYSIS
5.10.1
OEM INVESTMENT PRIORITIES
5.10.2
FLEET PARTNERSHIP STRATEGIES
5.11
TOTAL COST OF OWNERSHIP & PAYBACK ANALYSIS
5.11.1
CNG VEHICLE VS. PETROL/DIESEL VEHICLE TCO
5.11.2
LNG TRUCK VS. DIESEL TRUCK TCO
5.11.3
PAYBACK PERIOD BY VEHICLE/APPLICATION
5.12
THREE-WHEELER POWERTRAIN TRANSITION & CNG MARKET OPPORTUNITY
5.12.1
CNG THREE-WHEELER ADOPTION HOTSPOTS AND FLEET ECONOMICS
5.12.2
OEM POWERTRAIN STRATEGIES
5.12.3
CNG-TO-EV TRANSITION ROADMAP
5.13
EUROPE-INDIA TRADE DEALS: IMPACT ANALYSIS
5.13.1
INTRODUCTION
5.13.2
EU TARIFFS
5.13.3
IMPORTS TO INDIA
5.13.4
EXPORTS TO INDIA
5.14
ISRAEL-US WAR IMPACT ON AUTOMOTIVE INDUSTRY
5.14.1
INTRODUCTION
5.14.2
DIRECT IMPACT
5.14.3
INDIRECT IMPACT
5.14.4
RISE IN FUEL PRICES
6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
6.1
KEY EMERGING TECHNOLOGIES
6.1.1
TYPE IV COMPOSITE CNG CYLINDERS
6.1.2
ADVANCED SEQUENTIAL GAS INJECTION
6.1.3
DUAL-FUEL CNG–DIESEL SYSTEMS
6.1.4
BIO-CNG/RENEWABLE NATURAL GAS INTEGRATION
6.1.5
AI- & SOFTWARE-ENABLED GAS-FUEL CONTROL
6.2
COMPLEMENTARY TECHNOLOGIES
6.2.1
CNG/LNG FUEL INJECTION ECUS
6.2.2
PRESSURE REGULATORS & REDUCERS
6.2.3
ON-BOARD FUEL-LEVEL & PRESSURE MONITORING
6.3
ADJACENT TECHNOLOGIES
6.3.1
FAST-FILL CNG COMPRESSORS & DISPENSERS
6.3.2
THREE-WAY CATALYTIC CONVERTERS & AFTERTREATMENT
6.3.3
DIRECT-INJECTION CNG/LNG SYSTEMS
6.4
TECHNOLOGY/PRODUCT ROADMAP
6.4.1
SHORT-TERM (2026–2027) | FOUNDATION & EARLY COMMERCIALIZATION
6.4.2
MID-TERM (2028–2030) | EXPANSION & STANDARDIZATION
6.4.3
LONG-TERM (2031–2035+) | MASS COMMERCIALIZATION & DISRUPTION
6.5
POWERTRAIN ARCHITECTURE
6.5.1
DEDICATED GAS ENGINES
6.5.2
DUAL-FUEL ENGINES
6.5.3
HPDI
6.5.4
SPARK-IGNITED ENGINES
6.5.5
GAS-ELECTRIC HYBRID ENGINES
6.6
IMPACT OF AI ON CNG VEHICLES MARKET
6.6.1
TOP USE CASES & MARKET POTENTIAL
6.6.2
BEST PRACTICES FOLLOWED BY MANUFACTURERS/OEMS IN CNG VEHICLES MARKET
6.6.3
CASE STUDIES RELATED TO AI IMPLEMENTATION IN CNG VEHICLES MARKET
6.6.4
INTERCONNECTED ECOSYSTEM & IMPACT ON MARKET PLAYERS
6.6.5
CLIENTS’ READINESS TO ADOPT AI-INTEGRATED CNG VEHICLES
6.7
PATENT ANALYSIS
7
REGULATORY LANDSCAPE & SUSTAINABILITY INITIATIVES
7.1
REGIONAL REGULATIONS & COMPLIANCE
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
INDUSTRY STANDARDS
7.2
SUSTAINABILITY INITIATIVES
7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES
8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
8.1
DECISION-MAKING PROCESS
8.2
BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA
8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS
8.2.2
BUYING CRITERIA
8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES
8.4
UNMET NEEDS OF VARIOUS END-USE USERS/END-USE INDUSTRIES
9
CNG VEHICLES MARKET, BY ENGINE/SYSTEM TYPE
Market Size, Volume & Forecast – USD Million9.1
INTRODUCTION
9.2
DEDICATED FUEL ENGINES
9.3
BI-FUEL ENGINES
9.4
DUAL-FUEL ENGINES
9.5
KEY PRIMARY INSIGHTS
10
CNG VEHICLES MARKET, BY FITTING TYPE
Market Size, Volume & Forecast – USD Million10.1
INTRODUCTION
10.2
OE-FITTED
10.3
AFTERMARKET
10.4
KEY PRIMARY INSIGHTS
11
CNG AND LNG VEHICLES MARKET, BY FUEL TYPE
Market Size, Volume & Forecast – USD Million11.1
INTRODUCTION
11.2
CNG
11.3
LNG
11.4
KEY PRIMARY INSIGHTS
12
CNG VEHICLES MARKET, BY KIT TYPE
Market Size, Volume & Forecast – USD Million12.1
INTRODUCTION
12.2
VENTURI
12.3
SEQUENTIAL
12.4
KEY PRIMARY INSIGHTS
13
CNG AND LNG VEHICLES MARKET, BY VEHICLE TYPE
Market Size, Volume & Forecast – USD Million13.1
INTRODUCTION
13.2
PASSENGER CARS
13.3
LIGHT COMMERCIAL VEHICLES
13.4
HEAVY COMMERCIAL VEHICLES
13.5
KEY PRIMARY INSIGHTS
14
CNG VEHICLES MARKET, BY TANK TYPE
Market Size, Volume & Forecast – USD Million14.1
INTRODUCTION
14.2
TYPE
14.3
TYPE
14.4
TYPE
14.5
TYPE
14.6
KEY PRIMARY INSIGHTS
15
CNG AND LNG VEHICLES MARKET, BY REGION
Market Size, Volume & Forecast – USD Million15.1
ASIA PACIFIC
15.1.1
CHINA
15.1.2
JAPAN
15.1.3
INDIA
15.1.4
SOUTH KOREA
15.1.5
THAILAND
15.1.6
INDONESIA
15.2
EUROPE
15.2.1
GERMANY
15.2.2
FRANCE
15.2.3
SPAIN
15.2.4
ITALY
15.2.5
RUSSIA
15.2.6
UK
15.2.7
TURKEY
15.3
NORTH AMERICA
15.3.1
US
15.3.2
CANADA
15.3.3
MEXICO
15.4
REST OF THE WORLD
15.4.1
BRAZIL
15.4.2
SOUTH AFRICA
16
COMPETITIVE LANDSCAPE
16.1
OVERVIEW
16.2
KEY PLAYER STRATEGIES/RIGHT TO WIN
16.3
MARKET SHARE ANALYSIS,
16.3.1
OEM
16.3.2
OEM
16.3.3
OEM
16.3.4
OEM
16.3.5
OEM
16.4
REVENUE ANALYSIS OF TOP LISTED/PUBLIC PLAYERS,
16.5
BRAND/PRODUCT COMPARISON
16.6
COMPANY VALUATION & FINANCIAL METRICS
16.7
COMPANY EVALUATION MATRIX: KEY PLAYERS,
16.7.1
STARS
16.7.2
EMERGING LEADERS
16.7.3
PERVASIVE PLAYERS
16.7.4
PARTICIPANTS
16.7.5
COMPANY FOOTPRINT: KEY PLAYERS,
16.7.5.1
COMPANY FOOTPRINT
16.7.5.2
REGION FOOTPRINT
16.7.5.3
FUEL TYPE FOOTPRINT
16.7.5.4
VEHICLE TYPE FOOTPRINT
16.7.5.5
ENGINE/SYSTEM TYPE FOOTPRINT
16.8
COMPANY EVALUATION MATRIX: START-UPS/SMES,
16.8.1
PROGRESSIVE COMPANIES
16.8.2
RESPONSIVE COMPANIES
16.8.3
DYNAMIC COMPANIES
16.8.4
STARTING BLOCKS
16.8.5
COMPETITIVE BENCHMARKING: START-UPS/SMES,
16.8.5.1
DETAILED LIST OF KEY START-UPS/SMES
16.8.5.2
COMPETITIVE BENCHMARKING OF KEY START-UPS/SMES
16.9
COMPETITIVE SCENARIO
16.9.1
NEW PRODUCT DEVELOPMENT
16.9.2
DEALS
16.9.3
EXPANSIONS
16.9.4
OTHER DEVELOPMENTS
17
COMPANY PROFILES
17.1
KEY PLAYERS
17.1.1
MARUTI SUZUKI
17.1.1.1
BUSINESS OVERVIEW
17.1.1.2
PRODUCTS OFFERED
17.1.1.3
RECENT DEVELOPMENTS
17.1.1.4
MNM VIEW
17.1.2
TATA MOTORS
17.1.3
HYUNDAI MOTOR COMPANY
17.1.4
TOYOTA MOTOR CORPORATION
17.1.5
VOLKSWAGEN GROUP
17.1.6
ŠKODA AUTO
17.1.7
FIAT
17.1.8
SEAT
17.1.9
RENAULT
17.1.10
NISSAN
17.1.11
IRAN KHODRO
17.1.12
SAIPA
(*COMPANY PROFILE WOULD COVER BUSINESS OVERVIEW, PRODUCTS OFFERED, DEALS, AND MNM VIEW)
*DETAILS ON BUSINESS OVERVIEW, PRODUCTS OFFERED, DEALS, AND MNM VIEW MIGHT NOT BE CAPTURED IN THE CASE OF UNLISTED COMPANIES.
17.2
OTHER KEY PLAYERS
(*QUALITATIVE WRITE-UP WOULD BE PROVIDED FOR OTHER KEY PLAYERS)
18
RESEARCH METHODOLOGY
18.1
RESEARCH DATA
18.1.1
SECONDARY DATA
18.1.1.1
KEY DATA FROM SECONDARY SOURCES
18.1.2
PRIMARY DATA
18.1.2.1
KEY DATA FROM PRIMARY SOURCES
18.1.2.2
KEY PRIMARY PARTICIPANTS
18.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS
18.1.2.4
KEY INDUSTRY INSIGHTS
18.2
MARKET SIZE ESTIMATION
18.2.1
BOTTOM-UP APPROACH
18.2.2
TOP-DOWN APPROACH
18.2.3
BASE NUMBER CALCULATION
18.3
MARKET FORECAST APPROACH
18.3.1
SUPPLY SIDE
18.3.2
DEMAND SIDE
18.4
DATA TRIANGULATION
18.5
FACTOR ANALYSIS
18.6
RESEARCH ASSUMPTIONS
18.7
RESEARCH LIMITATIONS & RISK ASSESSMENT
19
APPENDIX
19.1
DISCUSSION GUIDE
19.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
19.3
CUSTOMIZATION OPTIONS
19.4
RELATED REPORTS
19.5
AUTHOR DETAILS
The study involved four major activities to estimate the current size of the CNG vehicles market. We conducted exhaustive secondary research to collect information on the market, peer, and child markets. Next, we validated these findings and assumptions and sized them with industry experts across value chains through primary research. The team used top-down and bottom-up approaches to estimate the total market size. Thereafter, the team used market breakdown and data triangulation to estimate the market size of segments and subsegments.
Secondary ResearchIn the secondary research process, various sources such as company annual reports, investor presentations, press releases, industry association publications (for example, International Organization of Motor Vehicle Manufacturers (OICA), European Automobile Manufacturers’ Association (ACEA), National Highway Traffic Safety Administration (NHTSA), European Commission, Society of Automotive Engineers (SAE International), United Nations Economic Commission for Europe (UNECE), International Energy Agency (IEA)), government publications, technical articles, white papers, journals, trade websites, company product brochures, technical handbooks, and databases (for example, MarkLines and Factiva) have been used to identify and collect information for an extensive commercial study of the global CNG and LNG vehicles landscape. The research covers CNG passenger cars and light commercial vehicles (LCVs), and LNG heavy commercial trucks, including vehicle sales, OEM portfolios, powertrain technologies, fueling infrastructure, regulations, and market developments.
Primary ResearchWe conducted extensive primary research after understanding the CNG vehicle landscape through secondary research. Several primary interviews were conducted with market experts from both demand (automotive OEMs, passenger-car and LCV manufacturers, heavy commercial vehicle manufacturers, fleet operators, and logistics companies) and supply (gas engine and fuel-system manufacturers, Tier-1 automotive suppliers, CNG/LNG storage-system manufacturers, fuel injector and ECU suppliers, refueling infrastructure providers, and gas companies) sides across Asia Pacific, Europe, North America, and the Rest of the World. We conducted approximately 74% and 26% of primary interviews from the demand and supply sides, respectively. We collected primary data through questionnaires, emails, and telephonic interviews. The interviews focused on CNG and LNG vehicle adoption by vehicle type, fuel-system configuration, engine technology, fuel storage capacity, vehicle range, pricing, fuel efficiency, refueling infrastructure, regulatory requirements, technology adoption, OEM strategies, and supplier strategies.
In the canvassing of primary data, various departments within organizations, such as sales, marketing, operations, engineering, product development, fleet management, and administration, were covered to provide a holistic viewpoint in this report. After interacting with industry experts, we also conducted brief sessions with highly experienced independent consultants to reinforce the findings from primary data. These, along with in-house subject-matter experts’ opinions, led to the findings described in the remainder of this report.
Breakdown of Primaries

Note 1: Others include subject-matter experts (SMEs), engineers, consultants, and business development professionals.
Note 2: Company tiers are based on the value chain; company revenues are not considered.
To know about the assumptions considered for the study, download the pdf brochure
We used both top-down and bottom-up approaches to estimate and validate the total size of the CNG vehicles market. We also used these methods extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
CNG Vehicles Market: Top-Down and Bottom-Up Approach
After arriving at the overall market size using the market size estimation processes explained above, we split the market into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics for each market segment and subsegment, we employed data triangulation and market breakdown procedures, where applicable. We triangulated the data by examining factors and trends from both the demand and supply sides.
A CNG or LNG vehicle is a road vehicle powered by compressed natural gas (CNG) or liquefied natural gas (LNG). CNG vehicles use natural gas stored in high-pressure cylinders and are primarily used in passenger cars and light commercial vehicles, while LNG vehicles use cryogenically stored natural gas and are mainly used in heavy commercial trucks requiring longer driving ranges. The vehicle system includes the gas storage tank, fuel lines, pressure regulator or vaporizer, fuel injectors, engine, electronic control unit (ECU), and associated safety components that deliver and control the fuel. The market includes factory-fitted CNG passenger cars and LCVs and factory-fitted LNG heavy commercial trucks, including vehicles compatible with renewable fuels such as Bio-CNG and Bio-LNG.
With the given market data, MarketsandMarkets offers customizations to meet company-specific needs.


PRODUCT DIRECTOR, WEASLER
Global Provider of Industrial Actuation & Control Solutions
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Vice President
A global technology company that develops safer, greener and more connected solutions.
We contracted with MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our interest in the Fleet Management space. The team successfully completed the work on time and at the pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with us to help us get the visibility we needed to make an investment.
We have subsequently used MarketsandMarkets again related to Smart Cities to good results.